
Oct 08, 2026
By Transpire Insight
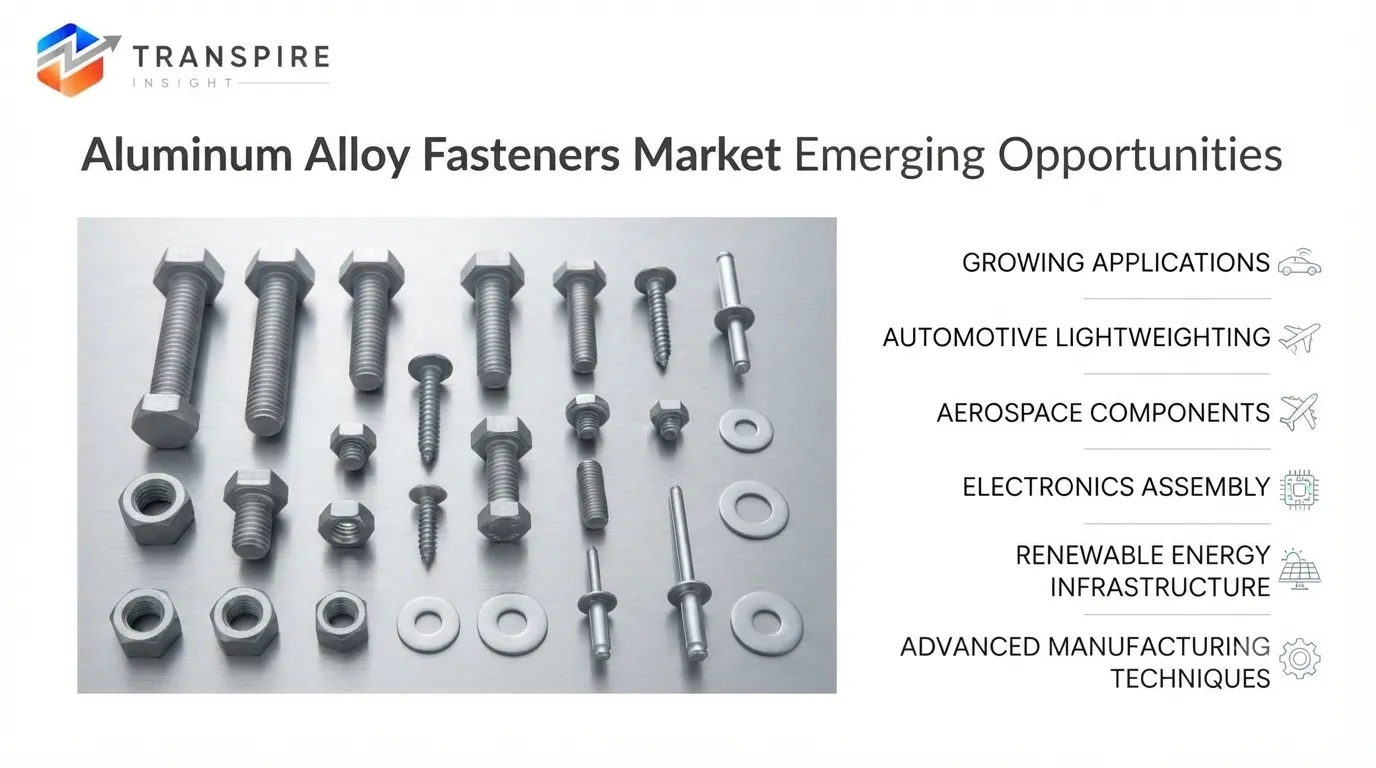
Description
According to a research report published by Transpire Insight, the aluminum alloy fasteners market size is projected to grow from USD 6.11 billion in 2026 to USD 9.8 billion by 2035, at a CAGR of 6.85% during the forecast period 2027-2035. Vehicle lightweighting mandates, accelerating electric vehicle (EV) production, expanding commercial aircraft assembly, and strict fuel-efficiency standards are driving adoption of high-strength aluminum alloy fasteners to replace traditional steel components.
Introduction
The aluminum alloy fasteners market plays a vital role in modern aerospace, automotive, electronics, and construction applications. Valued for their high strength-to-weight ratio, superior corrosion resistance, non-magnetic properties, and electrical conductivity, aluminum alloy fasteners allow manufacturers to achieve critical weight savings without compromising joint integrity. Driven by decarbonization goals, fleet electrification, and rapid industrialization, key producers are actively innovating specialized anodized, high-purity, and heat-treated alloy fasteners for demanding applications.
Recent Development News
January 2026: Howmet Aerospace expanded its automated production capacity for high-strength 7000-series aluminum alloy structural rivets and bolts to meet rising commercial airframe build rates.
February 2026: Lisi Aerospace partnered with major European electric vehicle manufacturers to deploy specialized corrosion-resistant aluminum alloy threaded fasteners for battery enclosure assemblies.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Aluminum Alloy Fasteners Market Size & Statistics
The Market Size for Aluminum Alloy Fasteners Was Estimated to be Worth USD 6.11 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 6.85% between 2026 and 2035.
The Aluminum Alloy Market Size is anticipated to reach USD 9.8 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 36% of the aluminum alloy market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 7.8% in the aluminum alloy market.
Regional Growth and Demand Analysis by Transpire Insight
North America is the dominant region. Consolidation is reshaping the North American base too; vertical-integration moves, such as a heavy-duty fastener producer acquiring a domestic manufacturing facility to localize supply for steel fabrication and commercial construction, reflect a broader push toward shorter, more resilient supply chains. In Europe, buyers are increasingly bound by CE and construction-product-regulation compliance for aluminum fasteners used in structural and self-tapping applications, pushing suppliers toward certified, application-specific product lines rather than commodity hardware. Both regions are also seeing procurement shift toward "local-for-local" sourcing as manufacturers hedge against trade-policy risk, favoring qualified regional partners over low-cost imports.
Asia-Pacific is the fastest-growing region. China's manufacturing scale and India's expanding automotive and electronics hubs are the primary engines, alongside Southeast Asia's growing role as an assembly base. Rising EV production across the region is a particularly strong driver, since battery enclosures, chassis structures, and powertrain assemblies all favor aluminum over steel for weight reduction. At the same time, the broader market is tilting toward higher-value products; premium and specialty fasteners are projected to grow from roughly a third of total market value to over half within a decade, meaning Asia-Pacific's growth is increasingly weighted toward certified, traceable hardware rather than basic commodity fasteners.
Top 15 Trends in the Aluminum Alloy Fasteners Market
Automotive lightweighting boosts aluminum fastener adoption.
Automakers are replacing heavier steel fasteners with aluminum alternatives across EV and combustion platforms, cutting vehicle weight to meet fuel-economy and emissions targets today.
EV production accelerates aluminum fastener demand.
Rising electric vehicle output is intensifying demand for aluminum fasteners in battery enclosures, chassis structures, and powertrain assemblies, where reduced weight directly extends driving range.
Premium and specialty fasteners gaining value share
Certified, application-specific fasteners are capturing a growing share of total market value as end users prioritize traceability and reliability over unit cost across industries.
Local-for-local sourcing reshapes regional supply chains.
North American and European buyers are shifting procurement toward regional suppliers to reduce trade exposure, prompting manufacturers to expand localized aluminum fastener production capacity further.
Sustainability push drives aluminum recycling adoption.
Manufacturers are adopting recycled aluminum feedstock and eco-friendly production processes to cut carbon footprints, aligning with tightening environmental regulations across automotive and construction end markets.
Data center and 5G infrastructure builds demand.
Hyperscale data center construction and 5G network rollouts are creating fresh demand for lightweight, corrosion-resistant aluminum fasteners in server racks, towers, and enclosures worldwide.
List of Top 25 Companies Leading the Aluminum Alloy Fasteners Market
1. Howmet Aerospace Inc.
World leader in precision structural fasteners and engineered components for aviation.
Founded: 2020 | HQ: Pittsburgh, Pennsylvania, USA.
Why It Ranks: Unmatched market share in high-strength aerospace aluminum and titanium fasteners.
Regional Dominance: Holds extensive manufacturing and distribution dominance across North American and European aerospace hubs.
Product Line: Aerospace-grade aluminum structural bolts, lockbolts, rivets, and high-temp blind fasteners.
2. LISI Aerospace (LISI Group)
Premier supplier of high-performance assembly components for commercial and military aircraft.
Founded: 1968 | HQ: Belfort, France.
Why It Ranks: Leading position in specialty structural aluminum and titanium fasteners across Europe.
Regional Dominance: Strong commercial presence and long-standing supplier relationships throughout the European continent.
Product Line: Structural aluminum screws, hi-lite pins, nuts, inserts, and clip fasteners.
3. Böllhoff Group
specialist in innovative fastening, joining, and assembly technology systems.
Founded: 1877 | HQ: Bielefeld, Germany.
Why It Ranks: Key innovator in lightweight aluminum thread inserts and blind rivet nuts.
Regional Dominance: Commands major industrial market share across Central Europe while expanding into Asia-Pacific.
Product Line: HELICOIL thread inserts, RIVKLE aluminum blind rivet nuts, and high-speed blind rivets.
4. Stanley Engineered Fastening
leader in precision attachment solutions serving automotive and electronics industries.
Founded: 1910 | HQ: Towson, Maryland, USA.
Why It Ranks: Broad commercial portfolio and massive production footprint across international industrial sectors.
Regional Dominance: Maintains strong operational and commercial presence across the Americas, Europe, and Asia.
Product Line: POP aluminum blind rivets, Avdel breakstem systems, and threaded inserts.
5. Precision Castparts Corp. (PCC Fasteners)
Critical manufacturer of complex, high-reliability structural fasteners for extreme applications.
Founded: 1953 | HQ: Portland, Oregon, USA.
Why It Ranks: Major aerospace supplier backed by Berkshire Hathaway’s vast industrial network.
Regional Dominance: Dominates North American defense and commercial aviation fastener procurement supply chains.
Product Line: High-tensile aluminum bolts, nuts, studs, pins, and custom structural hardware.
6. Illinois Tool Works Inc. (ITW)
Multi-industrial manufacturing titan producing specialized engineered fasteners for automotive assembly.
Founded: 1912 | HQ: Glenview, Illinois, USA.
Why It Ranks: Massive worldwide scale and extensive automotive OEM supply contract portfolio.
Regional Dominance: Controls major market share across North American and European automotive manufacturing sectors.
Product Line: Self-tapping aluminum screws, plastic-metal hybrid fasteners, clips, and panel attachments.
7. TriMas Corporation (TriMas Aerospace)
Designer and producer of highly engineered fasteners for aerospace and defense.
Founded: 1986 | HQ: Bloomfield Hills, Michigan, USA.
Why It Ranks: Strategic supplier of specialty, high-precision aluminum blind rivets and collar systems.
Regional Dominance: Robust production network concentrated across North America with worldwide aviation export reach.
Product Line: Monogram Aerospace rivets, Allfast solid aluminum rivets, and temporary assembly fasteners.
8. PennEngineering (PEM)
Pioneer and leader in self-clinching fastener technology and precision tooling.
Founded: 1942 | HQ: Danboro, Pennsylvania, USA.
Why It Ranks: Unmatched reputation for aluminum clinching hardware used in electronics and chassis.
Regional Dominance: Expansive footprint and technical service leadership across North America, Europe, and Asia.
Product Line: PEM aluminum self-clinching nuts, studs, standoffs, and captive panel screws.
9. Araymond Network
International leader in engineered automotive clip, bonding, and quick-connect attachment solutions.
Founded: 1865 | HQ: Grenoble, France.
Why It Ranks: Top-tier automotive supplier driving innovative lightweight metal-and-plastic fastening solutions for vehicles.
Regional Dominance: Deep operational dominance across European automotive hubs and expanding Latin American facilities.
Product Line: Aluminum spring clips, body panel fasteners, ground studs, and quick connectors.
10. EJOT Group
European specialist in high-precision joining technology for construction and automotive lightweighting.
Founded: 1922 | HQ: Bad Berleburg, Germany.
Why It Ranks: Renowned for specialized thread-forming screws designed for aluminum die-cast light alloys.
Regional Dominance: Holds a leading position in Western European construction and automotive assembly markets.
Product Line: ALTRACS self-tapping aluminum screws, EJOWELD friction-welded joints, and building fasteners.
Conclusion
The aluminum alloy fasteners market remains essential to modern transport and manufacturing sectors. Driven by aggressive vehicle lightweighting goals, burgeoning commercial aviation order books, and consumer electronics miniaturization, demand for durable 2000, 6000, and 7000-series alloy hardware continues to grow. Leading manufacturers that invest in advanced anti-corrosion coatings, cold-forming technology, and automated installation systems will maintain a strong competitive edge in this evolving market.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


