
Sep 24, 2026
By Transpire Insight
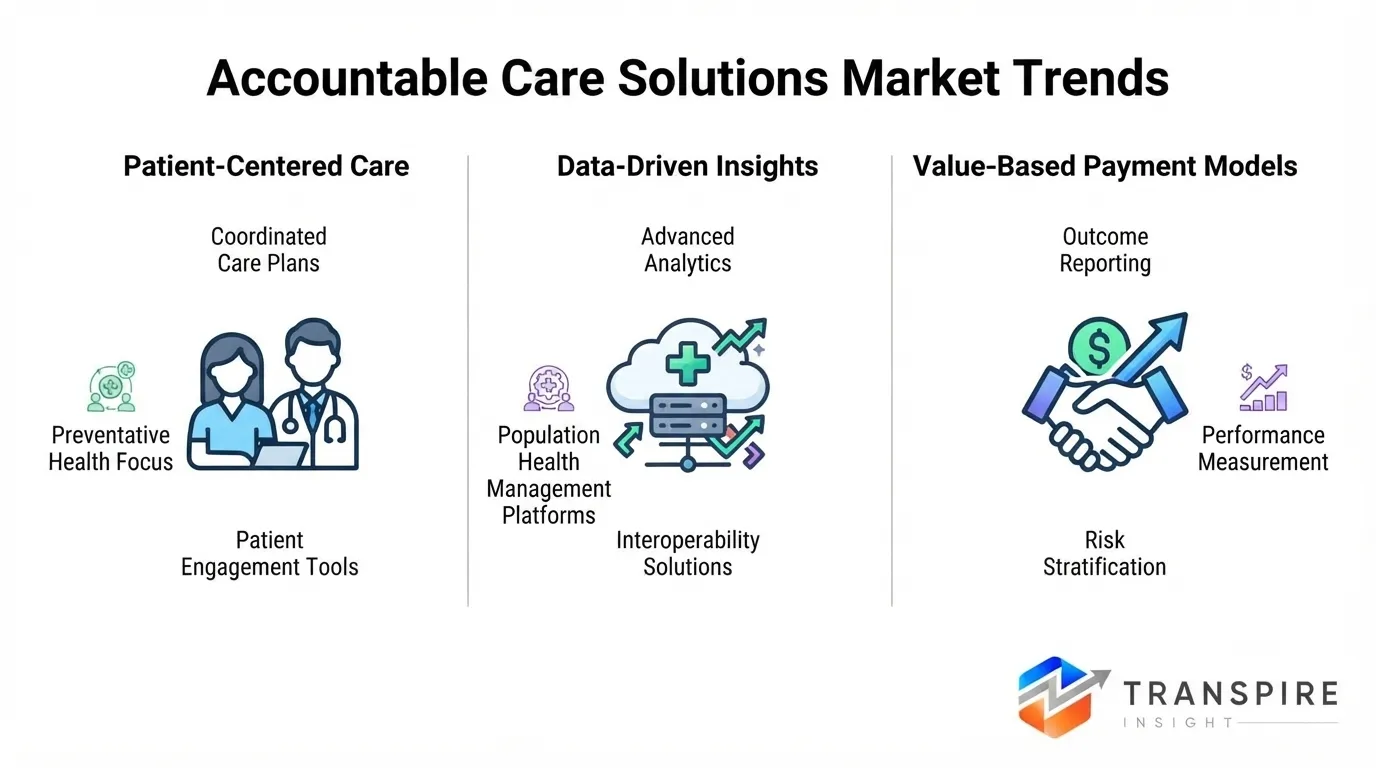
Description
According to a research report published by Transpire Insight, the accountable care solutions market size is projected to grow from USD 29.25 billion in 2026 to USD 70.37 billion by 2035, at a CAGR of 12.29% during the forecast period 2027-2035. Driven by the shift to value-based care, rising chronic disease burdens, escalating healthcare costs, and government incentives for interoperable data analytics.
Introduction
The Accountable Care Solutions (ACS) market delivers digital infrastructure, analytics platforms, and care management tools that enable healthcare providers and payers to implement value-based reimbursement models. By coordinating care pathways, managing population health, and reducing readmission rates, ACS aligns financial incentives with clinical outcomes. Driven by healthcare digitisation and regulatory mandates, the market is expanding rapidly to improve patient care efficiency and lower systemic costs.
Recent Development News
February 2026: CMS and commercial payers introduced expanded AI-driven risk stratification guidelines for Accountable Care Organizations (ACOs), accelerating cloud-based care management platform integrations.
May 2026: Leading digital health providers rolled out upgraded FHIR-native interoperability modules to streamline real-time clinical data exchange between health systems and payer networks.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Accountable Care Solutions Market Size & Statistics
The Market Size for Accountable Care Solutions Was Estimated to be Worth USD 29.25 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 12.29% between 2026 and 2035.
The Accountable Care Solutions Market Size is anticipated to reach USD 70.37 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 52% of the accountable care solutions market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 12% in the accountable care solutions market.
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance is anchored in strong regulatory momentum, particularly CMS's push to move Traditional Medicare beneficiaries into accountable care relationships, which has accelerated ACO formation across the US healthcare system. Large payer-provider ecosystems such as UnitedHealth's Optum, CVS Health's Aetna, and health IT majors like Oracle Health and Epic Systems continue to expand care coordination, analytics, and interoperability capabilities, reinforcing the region's advanced digital health infrastructure. High health insurance penetration, mature EHR adoption, and sustained investment in population health management platforms further cement North America's lead, even as payer-focused accountable care models gain additional traction alongside traditional provider-led approaches.
Asia-Pacific's rapid growth stems from aging populations in Japan and China, rising chronic disease burden, and expanding government investment in digital health infrastructure across the region. Countries such as India, through national digital health mission initiatives, and Australia, via value-based care pilots, are pushing payers and providers toward coordinated care models similar to Western ACO frameworks. Growing healthcare expenditure, rising smartphone-enabled health platform adoption, and increasing foreign vendor entry into APAC markets are compounding demand, positioning the region as the primary growth engine even though it currently trails North America and Europe in absolute market share.
Top 15 Trends in the Accountable Care Solutions Market
Value-Based Care Adoption
Healthcare providers increasingly shift from fee-for-service to value-based reimbursement models, using accountable care solutions to align financial incentives, reduce redundant procedures, and improve patient outcomes.
AI-Driven Risk Stratification
Vendors are embedding artificial intelligence into accountable care platforms to identify high-risk patients earlier, enabling proactive interventions, personalized care plans, and reduced avoidable hospital readmissions.
Payer-Provider Data Integration
Accountable care platforms increasingly ingest multi-payer claims and provider clinical data together, supporting seamless collaboration, shared risk management, and coordinated decision-making across previously siloed stakeholders.
Cloud-Based Solutions Surge
Cloud deployment is becoming the preferred delivery mode for accountable care solutions, offering healthcare organizations lower upfront costs, faster scalability, and easier system integration capabilities.
Predictive Analytics in Chronic Care
Predictive analytics tools now flag patients at risk of chronic disease complications earlier, enabling accountable care organizations to intervene proactively, reduce hospitalizations, and lower costs.
Downside-Risk Contracting Growth
Healthcare organizations are increasingly entering downside-risk contracts with payers, sharing financial accountability for patient outcomes, which drives greater demand for sophisticated accountable care analytics platforms.
List of Top 25 Companies Leading the Accountable Care Solutions Market
1. Epic Systems Corporation
Powers EHR and population health management for major health systems worldwide.
Founded: 1979 | HQ: Verona, Wisconsin, USA.
Why It Ranks: Dominates hospital electronic health records and integrated ACO clinical data workflows.
Regional Dominance: North America, with expanding deployments across Europe and the Middle East.
Product Line: EpicCare EHR, Healthy Planet Population Health, MyChart Patient Engagement Portal.
2. Oracle Corporation (Oracle Health)
Enhanced its healthcare footprint by fully integrating Cerner’s EHR network.
Founded: 1977 | HQ: Austin, Texas, USA.
Why It Ranks: Offers massive cloud scale for population health and enterprise data management.
Regional Dominance: presence with dominant footprints in North America and Europe.
Product Line: HealtheIntent Platform, Oracle Health EHR, Population Health Analytics Suite.
3. Optum (UnitedHealth Group)
Serves as the technology and services arm of UnitedHealth Group enterprise.
Founded: 2011 | HQ: Eden Prairie, Minnesota, USA.
Why It Ranks: Unrivaled integration of payer data, clinical care delivery, and risk analytics.
Regional Dominance: North America, with growing services across South America and Europe.
Product Line: Optum One Analytics, Population Health Management, Value-Based Care Solutions.
4. Athenahealth
Connects over 150,000 ambulatory providers through a cloud-based clinical platform network.
Founded: 1997 | HQ: Watertown, Massachusetts, USA.
Why It Ranks: Market leader in cloud EHR and clinical practice analytics for outpatient ACOs.
Regional Dominance: North America.
Product Line: athenaOne, athenaCare, Population Health Management Engine, Patient Engagement Tools.
5. eClinicalWorks
Supports over 150,000 physicians with integrated ambulatory care and EHR platforms.
Founded: 1999 | HQ: Westborough, Massachusetts, USA.
Why It Ranks: Provides affordable end-to-end accountable care software to independent provider practices.
Regional Dominance: North America, India, and the Middle East.
Product Line: Healow Insights, eClinicalWorks EHR, CCMR Population Health Management Suite.
6. Philips Healthcare
Leads health technology focused on continuous diagnostic and patient monitoring systems.
Founded: 1891 | HQ: Amsterdam, Netherlands.
Why It Ranks: Strong hybrid model combining enterprise remote monitoring with clinical care coordination.
Regional Dominance: Europe, North America, and Asia-Pacific.
Product Line: Philips Wellcentive, Enterprise Care Management, Acute Telehealth Solutions Suite.
7. GE HealthCare
Spun off as an independent medical technology powerhouse driving digital health solutions.
Founded: 1894 | HQ: Chicago, Illinois, USA.
Why It Ranks: Combines advanced medical imaging data with AI-enabled care management platforms.
Regional Dominance: reach spanning North America, Europe, Asia, and Latin America.
Product Line: Command Center Software, Edison AI Analytics Platform, Clinical Care Solutions.
8. Veradigm (formerly Allscripts)
Delivers clinical data networks connecting healthcare providers, health plans, and patients.
Founded: 1986 | HQ: Chicago, Illinois, USA.
Why It Ranks: Deep penetration in physician practices driving outpatient ACO risk performance capabilities.
Regional Dominance: North America and the United Kingdom.
Product Line: Veradigm FollowMyHealth, Care Management Suite, Practice Management Analytics Platform.
9. Inovalon
Fact: Processes billions of healthcare transactions through cloud analytics for risk alignment.
Founded: 1998 | HQ: Bowie, Maryland, USA
Why It Ranks: Essential provider of cloud analytics for health plans and ACO networks.
Regional Dominance: North America.
Product Line: ONE Platform, Healthcare Data Analytics, Quality & Risk Adjustment Solutions.
10. ZeOmega
Specializes in population health software serving top health plans and ACOs.
Founded: 2001 | HQ: Plano, Texas, USA.
Why It Ranks: Comprehensive Jiva platform drives enterprise care management and value-based outcomes.
Regional Dominance: North America.
Product Line: Jiva Healthcare Enterprise Platform, HealthUnity Interoperability, SDOH Social Care Platform.
Conclusion
The Accountable Care Solutions market represents a vital shift toward outcome-driven healthcare, replacing traditional volume-based payment models. By harnessing artificial intelligence, population health analytics, and cloud interoperability, these leading top 25 companies enable providers and payers to lower operational costs while improving patient health quality. As regulatory mandates tighten globally, digital accountable care infrastructure will remain central to sustainable and efficient healthcare delivery models.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


