
Sep 09, 2026
By Transpire Insight
Description
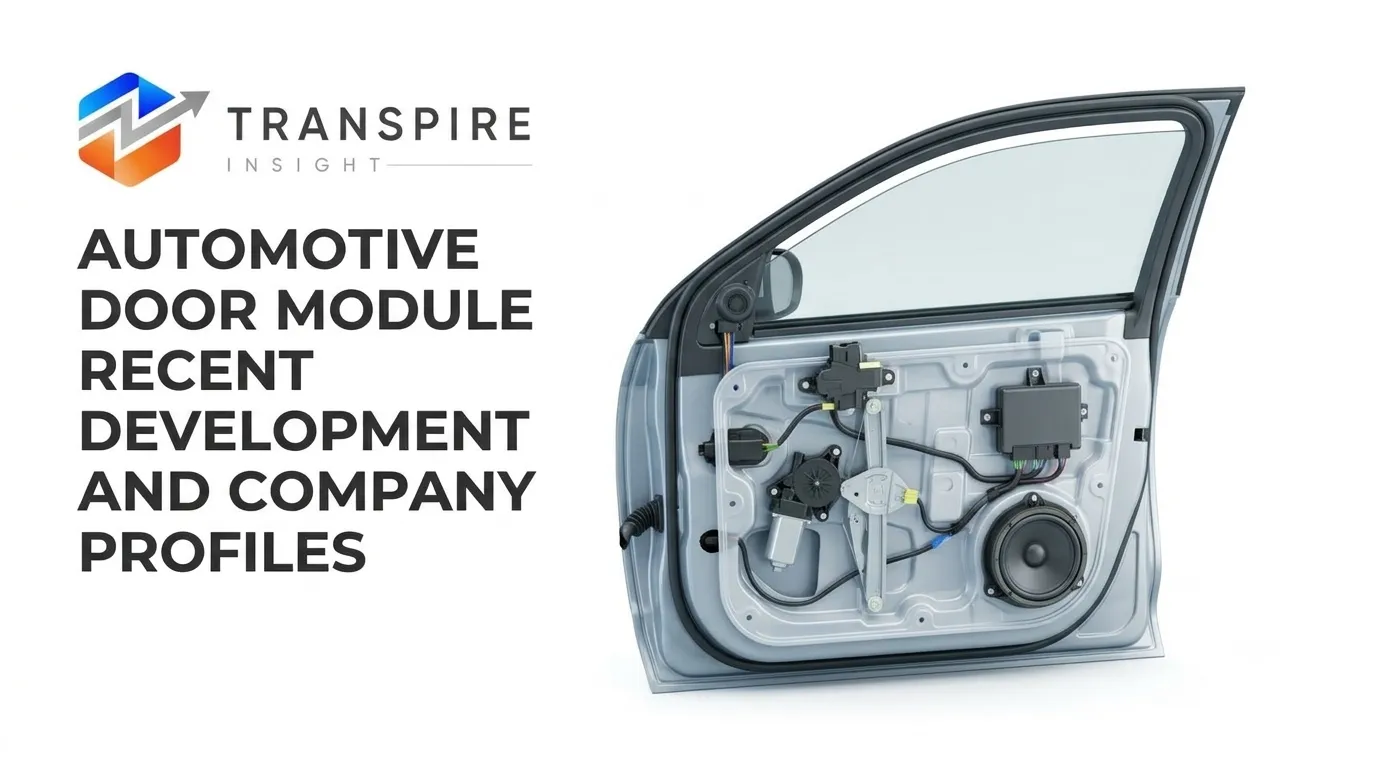
According to a research report published by Transpire Insight, the automotive door module market size is projected to grow from USD 36.25 billion in 2026 to USD 56.81 billion by 2035, at a CAGR of 6.20% during the forecast period 2027-2035. Rising vehicle production, acceleration of EV adoption, demand for smart automated door functions, OEM focus on lightweight modular assembly, and increasing integration of advanced safety and ADAS electronics drive the market.
Introduction
The automotive door module market is expanding rapidly due to rising vehicle production and advancing OEM modularization strategies. Modern door modules integrate structural carriers, window regulators, latches, wiring harnesses, and electronic control units into single, pre-tested sub-assemblies. This streamlines assembly line operations, lowers manufacturing costs, and reduces overall vehicle weight. Additionally, rising consumer demand for EV-specific smart access, improved acoustic insulation, and automated safety systems continues to drive market value globally.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Automotive Door Module Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
China's scale continues to anchor Asia Pacific's leadership, as the country recorded a marked rise in smart door module adoption while consumers increasingly favour connected, tech-forward comfort features over purely mechanical hardware. India, meanwhile, is emerging as the region's next major growth pocket: power window installations climbed sharply as automakers extended the feature into mid-range and even entry-level cars once reserved for premium trims. South Korea's Hyundai Mobis has reinforced this shift by expanding its integrated door-zone modules, which combine window, lock, and mirror control into a single high-integration unit for Hyundai-Kia platforms, lifting both average selling prices and technology complexity across the region.
North America's momentum, by contrast, is being driven less by production volume and more by electronics depth. The region benefits from strong semiconductor design capability and a rapidly expanding base of automotive, aerospace, and industrial R&D centres, pushing OEMs toward higher-complexity, sensor-rich door control units. Continental has led this shift with broad OEM partnerships across the region, while a vehicle fleet exceeding 290 million units continues to support elevated average selling prices for connected and luxury-oriented door features. Bosch has extended the same logic globally, expanding its Vehicle Motion Management portfolio to fold door control, braking, and steering into one centralized, software-defined architecture, enabling personalised entry experiences that North American OEMs are increasingly adopting first.
Top 15 Trends in the Automotive Door Module Market
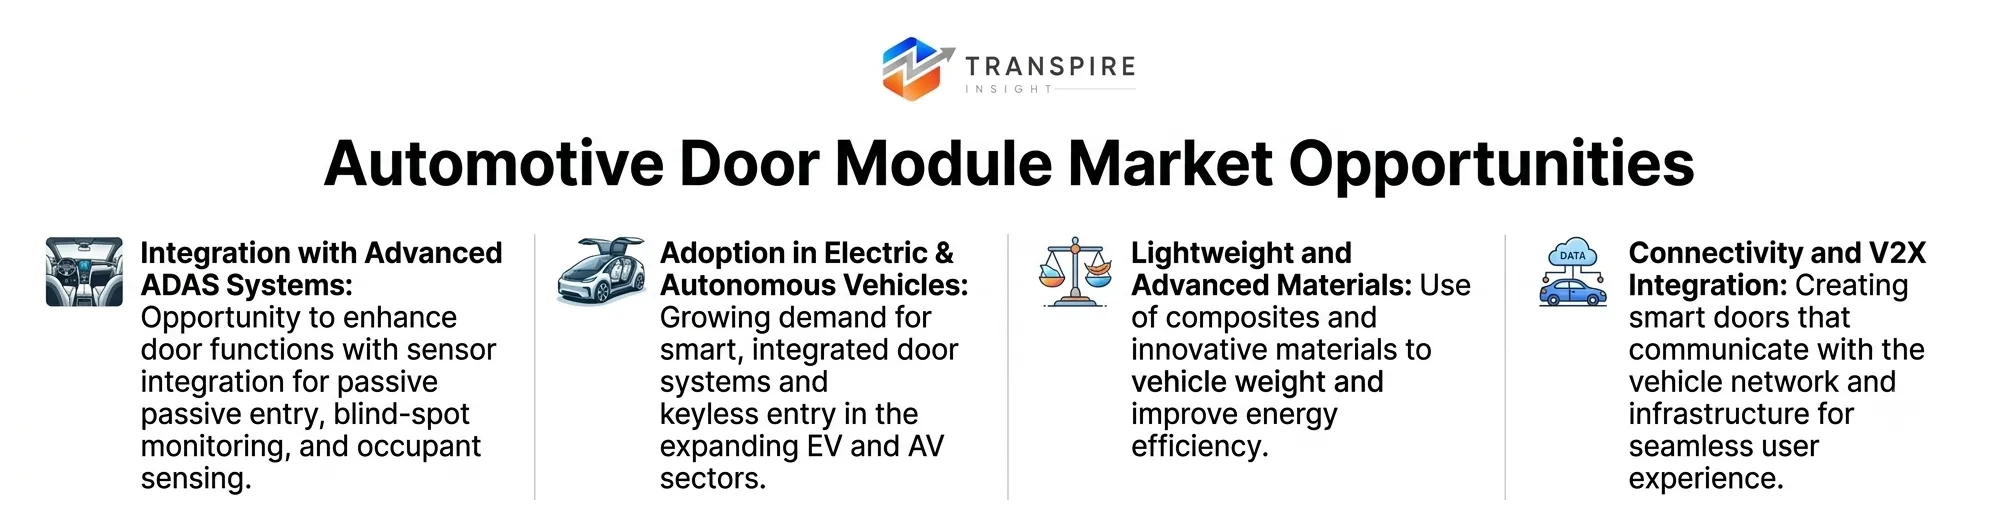
OEMs worldwide are replacing conventional mechanical door assemblies with integrated electronic modules combining regulators, latches, and control units, cutting assembly time and improving overall reliability.
Aisin recently opened a new Czech Republic facility expanding European production of power sliding door systems, responding to rising OEM demand for automated, comfort-driven access.
Roughly 74% of OEMs now prefer pre-assembled door modules over individually sourced parts, a shift that trims vehicle assembly time by nearly 18% on average.
North America is projected to post the fastest regional CAGR, at 10.02%, fuelled by strong semiconductor design, embedded-systems development, and expanding automotive R&D infrastructure.
India's market logged a 15% surge in power window installations as automakers extend the feature into mid-range and entry-level cars once reserved for higher trims.
China, the world's largest vehicle market, saw a 10% rise in smart door module adoption as consumers prioritize connected, tech-forward comfort features in new cars.
List of Top 25 Companies Leading the Automotive Door Module Market
World market leader in mechatronic door systems and power window regulators.
Founded: 1908 | HQ: Coburg, Germany.
Why It Ranks: Commands over 12% market share in automotive door modules.
Regional Dominance: Holds massive market share across European and North American OEM platforms.
Product Line: Integrated door modules, latch systems, power window regulators, and closure drives.
Multitask automotive giant supplying complex lightweight door carriers and latch systems.
Founded: 1957 | HQ: Aurora, Ontario, Canada.
Why It Ranks: Top Tier-1 player offering complete vehicle integration and manufacturing capabilities.
Regional Dominance: Dominates North American vehicle platforms with expansive presence in Europe.
Product Line: SmartAccess power doors, door modules, electronic latches, and structural carriers.
Key Toyota Group supplier specializing in power sliding door systems and latches.
Founded: 1965 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Top Tier-1 worldwide supplier with deep volume penetration in Asian markets.
Regional Dominance: Leads key original equipment manufacturer supply chains throughout Asia-Pacific.
Product Line: Power sliding door modules, door handles, door locks, and check links.
Pioneer in smart access solutions and electronic control units for doors.
Founded: 1871 | HQ: Hanover, Germany.
Why It Ranks: Leading provider of integrated automotive electronics and embedded door control software.
Regional Dominance: Dominates European automotive production lines with strong international manufacturing hubs.
Product Line: Power door control units, digital access systems, and smart sensors.
engineering powerhouse delivering electric motors and actuators for automated doors.
Founded: 1886 | HQ: Gerlingen, Germany.
Why It Ranks: Unrivaled scale in supplying electrical components and sensors to OEMs.
Regional Dominance: Strong leadership footprint across Europe, North America, and key Asian markets.
Product Line: Window lift drives, door actuators, control modules, and anti-pinch sensors.
Primary technology and module supplier for Hyundai Motor Group vehicle platforms.
Founded: 1977 | HQ: Seoul, South Korea.
Why It Ranks: Enormous supply volume serving top automotive original equipment manufacturers.
Regional Dominance: Dominates the South Korean market while rapidly expanding manufacturing sites.
Product Line: Integrated door trim modules, electronic latches, and power window systems.
Leader in vehicle electrical architecture and smart signal distribution inside doors.
Founded: 1994 | HQ: Dublin, Ireland.
Why It Ranks: Critical supplier of advanced electrical connectors and wiring harnesses for doors.
Regional Dominance: Strong technical and commercial presence across both North America and Europe.
Product Line: Door wiring harnesses, high-speed connectors, and body domain controllers.
specialist focusing exclusively on innovative closure systems and door modules.
Founded: 2008 | HQ: Troy, Michigan, USA.
Why It Ranks: Engineered light composite plastic door modules used by major OEMs.
Regional Dominance: Strong manufacturing footprint spanning North America, Europe, and key Asian hubs.
Product Line: Door modules, window regulators, latches, and advanced plastic carrier systems.
technology leader specializing in modern automotive side-door locking systems.
Founded: 1857 | HQ: Heiligenhaus, Germany.
Why It Ranks: Holds hundreds of patents in electronic latches and safety closure technologies.
Regional Dominance: Commands significant market share across European premium and mass-market vehicles.
Product Line: E-latches, power closures, door module latches, and active safety actuators.
Top-tier Japanese mobility supplier producing robust door electronics and actuators.
Founded: 1949 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Exceptional manufacturing quality and deep integration with major Asian vehicle platforms.
Regional Dominance: Dominant force in the Japanese and wider Asia-Pacific automotive industry.
Product Line: Window regulator motors, door control units, and keyless entry receivers.
Conclusion
The automotive door module market is undergoing a structural transformation driven by vehicle electrification, lightweighting, and advanced mechatronic integration. As automakers prioritize streamlined assembly and smart access features, Tier-1 suppliers are innovating composite materials and embedded electronics. Looking ahead, companies that combine lightweight carrier designs with software-driven smart door control units will continue leading the market and capturing long-term automotive manufacturing demand.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


