
Aug 01, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the automotive central gateway module market size is projected to grow from USD 1509.2 million in 2026 to USD 2308.2 million by 2035, at a CAGR of 7.5% during the forecast period 2026-2035. Rapid adoption of software-defined vehicles, expanding high-bandwidth Ethernet networks, and growing electrical/electronic complexity in electric and autonomous vehicles drive high demand for secure, centralized, and high-performance automotive gateway modules globally.
Introduction
The automotive Central Gateway Module (CGM) serves as the primary communication backbone in modern vehicles, enabling secure, seamless data routing across distinct domain architectures such as powertrain, infotainment, body electronics, and ADAS. As cars transition into connected software-defined platforms, CGMs process exponentially higher data volumes while protecting networks from cyber vulnerabilities. This report outlines key drivers, industry advancements, top manufacturers leading gateway innovation, and an overall industry conclusion.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Automotive Central Gateway Module Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Automotive Central Gateway Module Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
The United States and Mexico are North America's strongholds for automotive central gateway module markets, with the U.S. market representing the largest share in the region, due to the U.S. being the leading new vehicle producer and North America's leading gateway module market, and Mexico's becoming the leading assembly and export hub in the region, because of lower labor costs and being a close neighbor to the U.S. automakers. However, the current supply chain is far behind, and much of the critical silicon wafers, embedded memory, and high-layer-count PCBs are still imported mainly from Taiwan, South Korea, and Japan, leaving assembly firms vulnerable to long lead times and price fluctuations for the MCU. Despite sluggish growth in overall volumes, suppliers like Continental, Aptiv, and NXP Semiconductors are developing more cybersecurity and functional-safety certification capacity in the region, making the region a stronghold for high-dollar designs for vehicle gateways.
The major reason for the Asia Pacific's rapid growth is the market growth of China, Japan, and India, which are characterized by a strong automotive manufacturing footing with clear growth in the demand for connected and feature-rich passenger vehicles, compelling OEMs to shift towards more advanced gateway architectures. Chinese EV makers are increasingly using multiple gateway modules to provide over-the-air update capability and redundancy, in particular, while regional automakers are upgrading their smart transportation designs to Ethernet-based, zonal gateways, driven by government-backed smart transportation initiatives and tougher data-security laws. The region's rapidly increasing urbanization and disposable income are driving up demand for luxury and mid-segment vehicles with advanced connectivity features, solidifying Asia Pacific's role as the region's main contributor to the gateway module market.
Top 15 Trends in the Automotive Central Gateway Module Market
Proceed to Checkout to purchase the exclusive Automotive Central Gateway Module Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
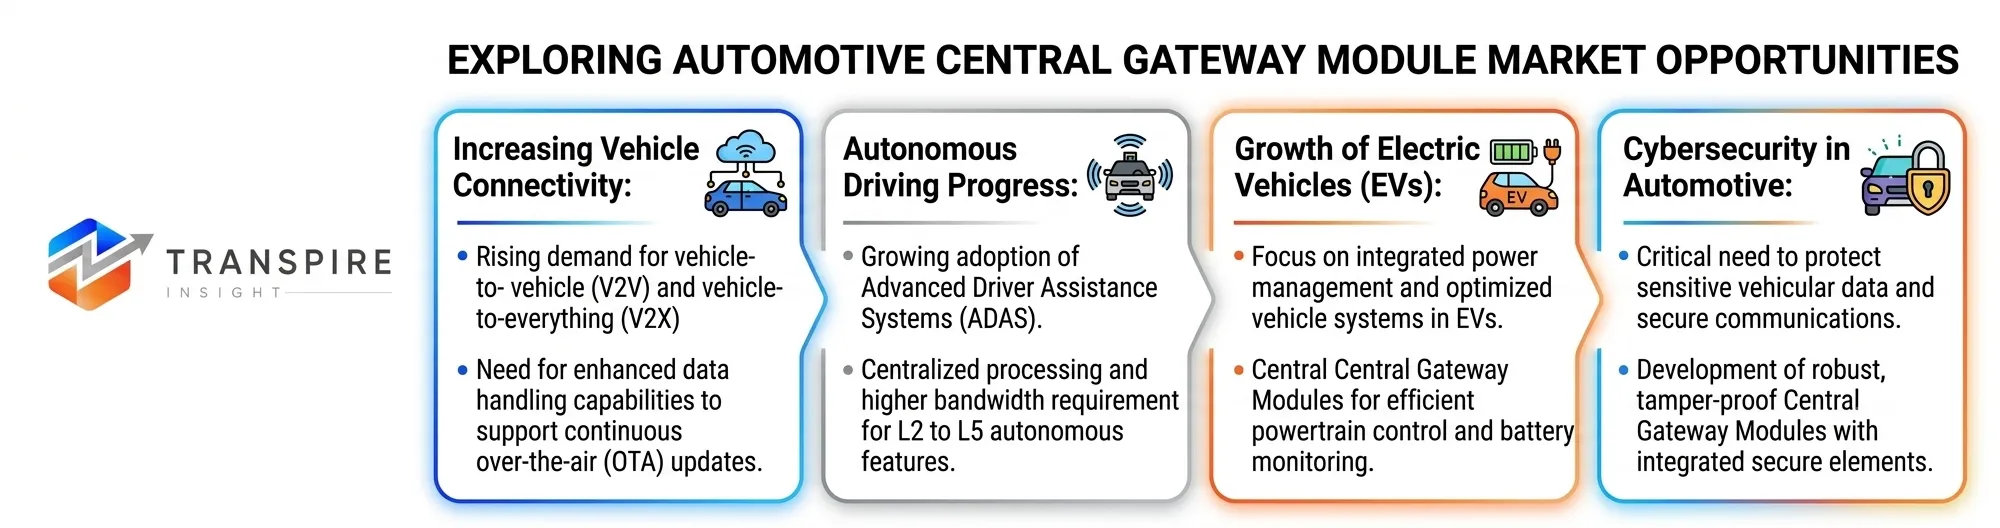
Automakers are consolidating dozens of domain controllers into fewer zonal gateways, cutting wiring complexity and cost while enabling centralized, software-defined vehicle control across all subsystems.
Automotive Ethernet is replacing CAN and LIN as the primary in-vehicle backbone, supporting the massive data loads generated by ADAS, infotainment, and connected vehicle-to-everything systems.
Gateway modules now host over-the-air update clients, allowing automakers to push software fixes, new features, and security patches remotely, cutting costly dealership recall visits significantly.
Rising data volumes from ADAS sensors, high-resolution infotainment displays, and camera systems are pushing gateway bandwidth needs from under 1 Gbps toward over 3 Gbps.
Electric vehicles increasingly carry two or three gateway modules for built-in redundancy, supporting high-bandwidth sensor data handling and improving fault tolerance across critical safety systems.
Advanced silicon wafers, embedded memory, and high-layer PCBs are sourced largely from Taiwan, South Korea, and Japan, exposing regional assemblers to extended component lead times.
List of Top 25 Companies Leading the Automotive Central Gateway Module Market
Customize the exclusive Automotive Central Gateway Module Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Aptiv PLC
Pioneer in Smart Vehicle Architecture, delivering scalable domain and zonal central gateways.
Founded: 1994 | HQ: Dublin, Ireland.
Why It Ranks: Market leader in high-compute hardware and software integration for next-generation mobility.
Regional Dominance: Strong market leadership across North American and European OEM supply chains.
Product Line: Smart vehicle architecture gateways, central domain controllers, and high-speed connectors.
2. Continental AG
Supplies advanced cybersecurity-enabled central gateways with integrated high-speed Ethernet routing capabilities.
Founded: 1871 | HQ: Hanover, Germany.
Why It Ranks: Exceptional engineering capabilities across vehicle network routing and secure domain architectures.
Regional Dominance: Enjoys massive commercial dominance across European and North American automotive markets.
Product Line: Central gateway control units, high-performance computers, and body domain gateways.
3. Delphi Automotive
Integrated under Aptiv, maintaining a long-standing legacy in robust electrical architectures.
Founded: 1994 | HQ: Gillingham, United Kingdom.
Why It Ranks: Historical pioneer in vehicle networking, diagnostic interface management, and bus routing.
Regional Dominance: Widespread enterprise footprint across European and commercial auto segments.
Product Line: Legacy central gateways, wiring distribution nodes, and bus interface modules.
4. Denso Corporation
Primary electronics supplier for Toyota, engineering ultra-reliable, high-grade gateway control units.
Founded: 1949 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Unmatched operational reliability and deep integration with leading Asian vehicle manufacturers.
Regional Dominance: Clear dominance across Japanese, East Asian, and North American passenger vehicles.
Product Line: Central gateway units, body control modules, and powertrain network gateways.
5. Fescaro Co., Ltd.
Specialized Korean automotive cybersecurity vendor producing hardware-software integrated secure gateway solutions.
Founded: 2016 | HQ: Seongnam, South Korea.
Why It Ranks: High-growth innovator delivering robust cybersecurity and gateway platforms for modern vehicles.
Regional Dominance: Emerging local market stronghold across South Korean automotive and mobility networks.
Product Line: Secure gateway controllers, embedded cybersecurity software, and ECU diagnostic tools.
6. HiRain Technologies
Prominent Chinese Tier-1 supplier delivering localized AUTOSAR-compliant gateway solutions to domestic OEMs.
Founded: 2003 | HQ: Beijing, China.
Why It Ranks: Key enabler of rapid software-defined vehicle adoption among Chinese electric vehicle makers.
Regional Dominance: Massive market presence and rapid expansion throughout the mainland Chinese automotive industry.
Product Line: Central gateway modules, domain controllers, AUTOSAR software stacks, and testing tools.
7. Hitachi Astemo
Formed via a mobility merger, producing high-performance central gateways for connected vehicle ecosystems.
Founded: 2021 | HQ: Tokyo, Japan.
Why It Ranks: Strong synergy of advanced powertrain, chassis, and electronic architecture technology capabilities.
Regional Dominance: Established market footprint in Japan with expanding OEM partnerships worldwide.
Product Line: Gateway control units, autonomous driving domain controllers, and connected mobility modules.
8. Infineon Technologies AG
Leading semiconductor manufacturer providing AURIX microcontrollers that power secure central vehicle gateways.
Founded: 1999 | HQ: Neubiberg, Germany.
Why It Ranks: Dominant provider of silicon, hardware security modules, and automotive microcontrollers.
Regional Dominance: market leader across European, North American, and Asian automotive electronics.
Product Line: AURIX microcontrollers, hardware security modules, and automotive power management ICs.
9. Lear Corporation
leader in electrical systems, delivering integrated central gateways and power distribution networks.
Founded: 1917 | HQ: Southfield, Michigan, USA.
Why It Ranks: Vast manufacturing scale and expertise in complex high-speed electrical architectures.
Regional Dominance: Dominant Tier-1 footprint across North American and European major automotive platforms.
Product Line: Central gateway modules, smart power distribution systems, and connectivity control units.
10. Magna International Inc.
Comprehensive mobility technology supplier offering integrated electronic architectures and central gateway control nodes.
Founded: 1957 | HQ: Aurora, Ontario, Canada.
Why It Ranks: Full-vehicle engineering expertise enabling seamless system-level integration of central gateway units.
Regional Dominance: Expansive manufacturing presence across North American, European, and Asian auto markets.
Product Line: Electronic control units, domain gateways, integrated ADAS controllers, and body modules.
Schedule a meeting with our market experts to discuss the exclusive Automotive Central Gateway Module Market report and identify the best research solution for your organization.
Conclusion
The automotive Central Gateway Module market is ripe for a critical shift as the software-defined vehicle, electrification, and cybersecurity requirements take hold. Central gateway modules are essential for securely routing cross-domain data as vehicle architectures evolve from CAN/LIN to high-bandwidth zonal Ethernet. Leading suppliers and semiconductor manufacturers are continuing to push the boundaries of innovation in advanced encryption, cloud connectivity, and scalable compute platforms, and it is clear that central gateway modules are the backbone of future autonomous and connected mobility, a resilient and intelligent solution that remains on course to evolve as the backbone of future mobility solutions.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


