
Jul 22, 2026
By Transpire Insight
Description
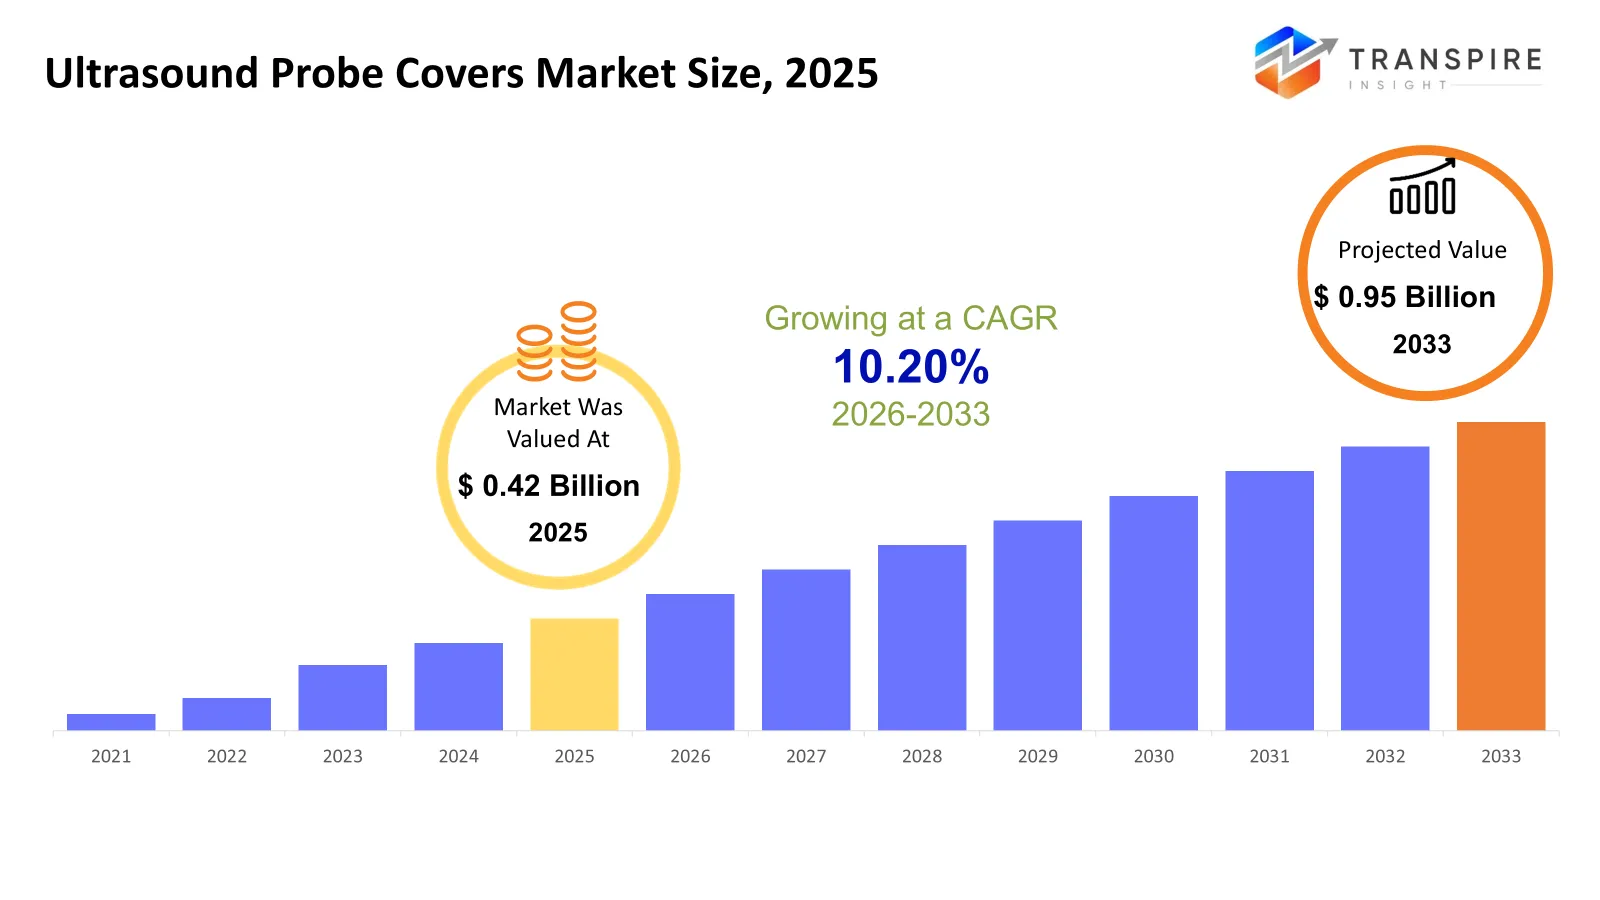
According to a research report published by Transpire Insight, the global ultrasound probe covers market size is projected to grow from USD 356.02 billion in 2026 to USD 413.00 billion by 2035, at a CAGR of 9.50% during the forecast period 2026-2035. The market is fueled by the increasing diagnostic ultrasound volumes worldwide and increased clinical interest in the prevention of hospital-acquired infections. Strict regulatory requirements for medical sterilisations are also pushing the demand for single-use protective barriers, along with the rise of handheld portable ultrasound (POCUS) devices.
Introduction
The global ultrasound probe covers market is growing at a quick pace, as the growing integration of diagnostic imaging in various clinical workflows continues to drive the market. These covers create a crucial sterile barrier between the patient and the ultrasound transducer, helping to reduce the risk of cross-infection when using the ultrasound device for invasive and non-invasive procedures. Regulatory constraints on hospital-acquired infections (HAIs), growing numbers of point-of-care ultrasound (POCUS) scans, and significant research and development of multi-functional, acoustically optimized polymer materials are all major factors driving up the market.
Recent Developments News
Download the exclusive Ultrasound Probe Covers Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Ultrasound Probe Covers Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
North America's dominance stems from a well-developed healthcare infrastructure and strict infection control norms, where hospitals and ambulatory surgical centers are bound by Joint Commission compliance requirements that mandate systematic probe cover use. The region's leadership is reinforced by rapid adoption of sterile, single-use, and non-latex covers, alongside consolidated procurement through Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs) that favor suppliers offering bundled, volume-based contracts. Replacement cycles for ultrasound transducers (typically 5-7 years) continue to drive periodic upgrades to next-generation cover geometries featuring anti-fog coatings and integrated acoustic coupling layers, particularly for TEE and intracavitary applications, commanding brand premiums across the U.S. market.
Asia Pacific's fastest-growth trajectory is fueled by expanding healthcare access, rising chronic and lifestyle disease incidence, and rapid modernization of medical facilities across China, Japan, and India. A major structural shift is supply chain localization, large markets like China and India are pushing to localize the manufacturing of medical consumables in response to global logistics disruptions and cost pressures, with China evolving from a pure consumption hub into a major manufacturing cluster for polymer conversion and contract manufacturing. India remains a major consumption center with a growing domestic manufacturing base, and expanding point-of-care ultrasound (POCUS) adoption across emergency medicine, anesthesiology, and critical care is decentralizing demand beyond traditional tertiary hospitals into diagnostic centers and outpatient clinics.
Top 15 Trends in the Ultrasound Probe Covers Market
Proceed to Checkout to purchase the exclusive Ultrasound Probe Covers Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
A clear trend toward sterile, single-use covers is emerging across applications, driven by infection prevention control committee mandates and elimination of reprocessing risks in acute care.
Disposable probe covers held the largest market share at 72% in 2025, favored for reducing cross-contamination risk without requiring sterilization between uses.
Non-latex materials are being adopted due to rising allergy awareness and stricter regulatory recommendations, with polyurethane, polyethylene, and polyisoprene alternatives improving biocompatibility and acoustic transparency.
Manufacturers are incorporating anti-fog coatings and integrated acoustic coupling layers, particularly for TEE and intracavitary applications, improving image quality and commanding brand premiums.
AI-powered vision systems and automated inspection tools ensure consistent manufacturing quality, reducing defects and improving sterility assurance for probe covers across production lines.
Point-of-Care Ultrasound expansion across diverse care settings, plus rising ultrasound-guided procedure volumes, structurally drives consumable demand for procedure-specific covers industry-wide.
List of Top 25 Leading Companies Dominating the Ultrasound Probe Covers Market
Customize the exclusive Ultrasound Probe Covers Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. B. Braun SE
A premier European healthcare supplier specializing in effective acute infection prevention systems.
Founded: 1839 | HQ: Melsungen, Germany.
Why It Ranks: Extensive global supply networks establish their sterile consumables across critical care units.
Regional Dominance: Deeply entrenched throughout European hospitals while steadily growing their Latin American footprint.
Product Line: Sterile surgical protective sheaths, regional anesthesia kits, and general ultrasound consumables.
2. Medline Industries, LP
This private medical powerhouse manufactures an expansive catalog of routine clinical supplies.
Founded: 1966 | HQ: Northfield, Illinois, USA.
Why It Ranks: High-volume institutional distribution agreements secure their place in thousands of hospitals.
Regional Dominance: Dominates the domestic United States healthcare market with extensive distribution networks.
Product Line: Polyurethane probe drapes, transmission gels, and point-of-care ultrasound procedure kits.
3. Cardinal Health Inc.
A vital healthcare services company distributing critical supplies to global providers daily.
Founded: 1971 | HQ: Dublin, Ohio, USA.
Why It Ranks: Comprehensive administrative logistics capabilities streamline bulk medical consumable fulfillment programs worldwide.
Regional Dominance: Highly influential across North American medical clinics and major ambulatory centers.
Product Line: Universal viral barrier covers, sterile procedure packs, and hospital sanitation equipment.
4. CIVCO Medical Solutions (Roper Technologies)
The undisputed gold standard specialist focusing purely on protective ultrasound accessory designs.
Founded: 1982 | HQ: Coralville, Iowa, USA.
Why It Ranks: Dedicated innovation in custom transducer safety yields superior market-wide clinical trust.
Regional Dominance: Global presence with unparalleled market penetration within Western radiology departments.
Product Line: CIV-Flex specialized sheaths, needle guidance systems, and transesophageal covers.
5. Parker Laboratories, Inc.
The worldwide leader in specialized conductive formulations and diagnostic accessory lines.
Founded: 1958 | HQ: Fairfield, New Jersey, USA.
Why It Ranks: Unrivaled brand equity in ultrasound gels naturally pulls high cover sales.
Regional Dominance: Ubiquitous brand recognition throughout North America, Europe, and the Middle East.
Product Line: Eclipse endocavity covers, clear scanning sheaths, and bactericidal cleaning products.
6. Ecolab Inc.
A global sustainability titan providing critical cross-contamination defenses across commercial industries.
Founded: 1923 | HQ: St. Paul, Minnesota, USA.
Why It Ranks: Unmatched operational expertise in institutional hygiene protocols drives hospital system integration.
Regional Dominance: Strong operational footprint throughout North America and major European metropolitan areas.
Product Line: Surgical equipment barriers, system drapes, and advanced medical device disinfectants.
7. 3M Healthcare (Solventum)
An independent medical innovator spun off to advance patient care pathways.
Founded: 2024 (Spun from 3M) | HQ: St. Paul, Minnesota, USA.
Why It Ranks: An advanced materials science background yields highly reliable polymer film barrier technologies.
Regional Dominance: Expansive global reach covering mature healthcare networks and developing regional economies.
Product Line: Tegaderm acoustic films, specialized surgical drapes, and infection prevention consumables.
8. Advance Medical Designs, Inc.
A focused manufacturer creating custom-engineered protective solutions for clinical facility workflows.
Founded: 1984 | HQ: Marietta, Georgia, USA.
Why It Ranks: Specialization in customized equipment draping fosters highly sticky hospital contract procurement.
Regional Dominance: Primed primarily for the United States healthcare delivery and surgery networks.
Product Line: General-purpose probe kits, custom-length drapes, and viral barriers.
9. Fairmont Medical Products Ltd
An international supplier delivering high-quality surgical innovations directly to global practitioners.
Founded: 1988 | HQ: Melbourne, Australia.
Why It Ranks: Agility in manufacturing niche clinical safety items fills critical regional gaps.
Regional Dominance: Commands substantial market share across the Oceania region and Southeast Asia.
Product Line: Sterile custom transducer sheaths, endoscopy accessories, and operating room consumables.
10. Sheathing Technologies, Inc.
A dedicated developer focusing entirely on premium infection prevention barrier technologies.
Founded: 1986 | HQ: Morgan Hill, California, USA.
Why It Ranks: Micro-niche focus guarantees high physical quality and rigorous clinical compliance standards.
Regional Dominance: Steady presence within specialized North American diagnostic clinics and imaging centers.
Product Line: Sheathes, sterile covers, non-latex endocavity guards, and customized specialty wraps.
Schedule a meeting with our market experts to discuss the exclusive Ultrasound Probe Covers Market report and identify the best research solution for your organization.
Conclusion
The global ultrasound probe market is highly concentrated with the leading 10 companies having the broader distribution network and new materials that are the benchmarks for international clinical applications. These companies process their product lines to meet stringent infection control regulations in the global market and are positioned to capitalize on the growing trend of point-of-care ultrasound, thereby reducing cross-contamination threats across the globe. In the future, their success will depend on their capacity to develop new technologies for polymers that are environmentally friendly, acoustically pure and latex-free, befitting the industry's transition to smaller, high-frequency diagnostic imaging systems.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


