
Jul 29, 2026
By Transpire Insight
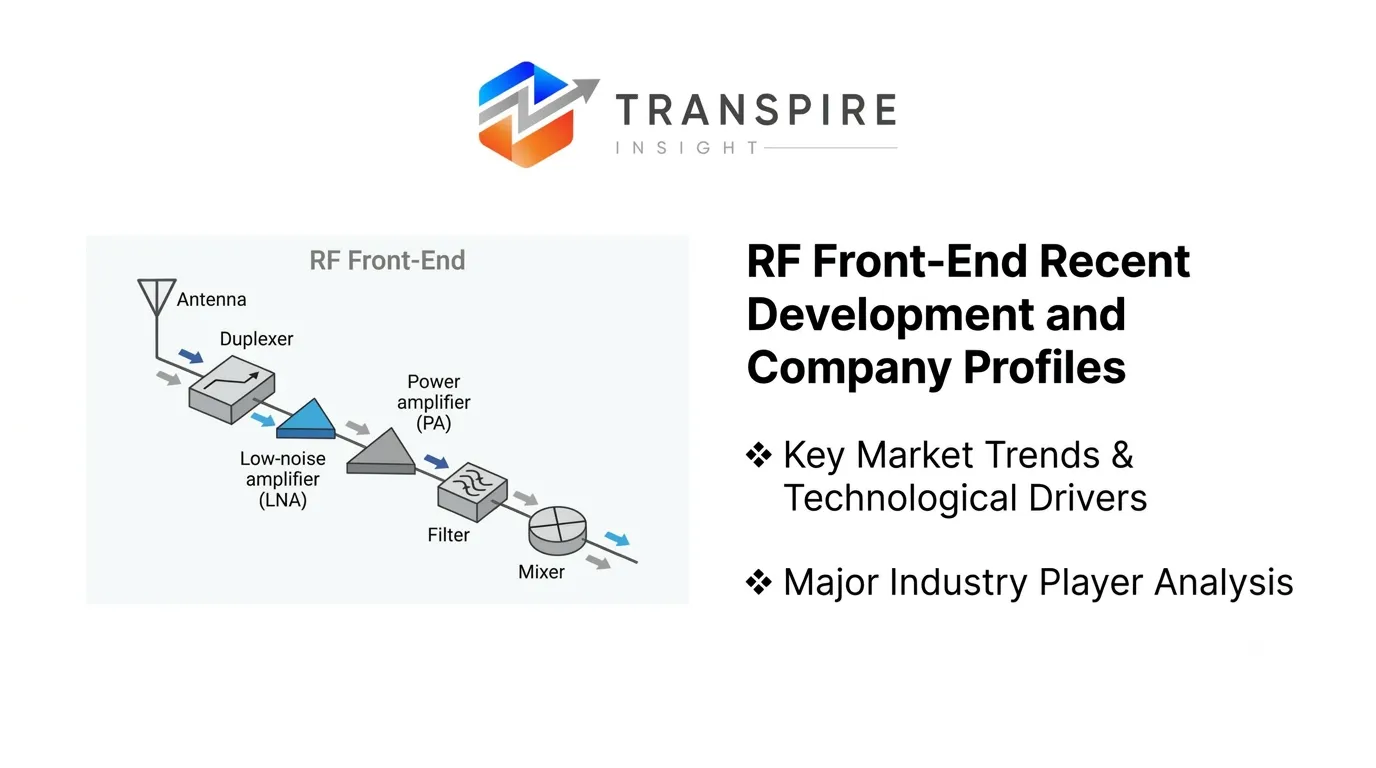
Description
According to a research report published by Transpire Insight, the RF front-end market size is projected to grow from USD 36.13 billion in 2026 to USD 93.11 billion by 2035, at a CAGR of 13.19% during the forecast period 2026-2035. The world's rapid adoption of 5G-Advanced is a key driver, as are early 6G architecture research, the surge in IoT ecosystems, and the incorporation of advanced and complex connectivity modules in autonomous electric vehicles.
Introduction
The Radio Frequency Front-End (RFFE) market is a central component of the telecommunications industry as it acts as a vital hardware layer between the digital baseband modems and real-world antennas. The rising need for high-frequency spectrum requires RFFE systems to handle complex signal amplification, switching, and filtering while keeping battery life intact and thermal footprint to a minimum. The industry is estimated to be more than $28 billion in 2026, moving toward single-package, fully integrated architectures. It is a key structural change to enable the high-bandwidth, dense requirements of next-generation infrastructure, smartphones, and edge platforms throughout the world.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
RF Front-End Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance rests on its dense concentration of RF component leaders, Qualcomm, Broadcom, and Skyworks among them, combined with rapid Wi-Fi 6E and early Wi-Fi 7 rollouts across enterprise and consumer devices through 2025 and 2026. The region's carriers continued expanding mid-band and mmWave 5G coverage in this period, pushing device makers to adopt front-end modules with wider bandwidth and multi-band support. Strong semiconductor fabrication investment, particularly in advanced packaging for GaN and GaAs power amplifiers, has kept North America's design and prototyping ecosystem ahead of demand, even as manufacturing itself increasingly shifts offshore. The U.S. market alone is projected to reach USD 6.48 billion in 2026, underscoring how smartphone refresh cycles, automotive radar adoption, and IoT connectivity are compounding demand across a mature but still-expanding base.
Asia Pacific's growth is anchored in China, Japan, South Korea, and India, where semiconductor manufacturing capacity and government-backed industrial policy are accelerating RF chip output. China's market is projected to reach USD 2.33 billion in 2026, Japan USD 1.58 billion, and India USD 1.11 billion, reflecting both domestic smartphone production scale and rising 5G base-station buildouts. China's expanding electric-vehicle sector is also pulling RF front-end demand into automotive radar and V2X connectivity, while South Korea's aggressive 5G densification keeps regional filter and amplifier orders high. Cost-efficient, vertically integrated supply chains, spanning gallium refining through module assembly, give Asia Pacific manufacturers a structural cost advantage that continues to draw new capacity investment from global players setting up regional fabrication lines.
Top 15 Trends in the RF Front-End Market
5G Network Expansion
Widespread 5G rollout across smartphones, base stations, and industrial equipment is driving demand for advanced RF front-end chips supporting multi-band, high-frequency signal processing worldwide today.
GaN and GaAs Adoption
Gallium nitride and gallium arsenide semiconductors are steadily replacing silicon in power amplifiers, delivering higher efficiency, better thermal performance, and stronger overall signal output quality.
Miniaturization and Integration
Manufacturers are increasingly integrating amplifiers, filters, switches, and duplexers into single compact modules, reducing device size while simplifying design and improving overall system reliability further.
Wi-Fi 6E and Wi-Fi 7 Adoption
Expanding Wi-Fi 6E and upcoming Wi-Fi 7 standards are pushing device makers toward wider bandwidth RF front-end modules capable of handling higher data throughput reliably.
Automotive Radar and V2X Connectivity
Automotive radar systems and vehicle-to-everything communication are expanding rapidly, requiring specialized RF front-end components for reliable, low-latency connectivity in modern connected and autonomous vehicles.
mmWave Frequency Band Expansion
Expansion into millimeter-wave frequency bands supports much higher 5G data speeds, though it demands advanced packaging, phased-array design, and premium-priced RF front-end module components overall.
List of Top 25 Companies Leading the RF Front-End Market
1. Qualcomm Incorporated
Dominates mobile platforms by supplying complete modem-to-antenna integrated RFFE systems.
Founded: 1985 | HQ: San Diego, California, USA.
Why It Ranks: Holds the largest single market share via top-tier smartphone design wins.
Regional Dominance: Highly influential globally, commanding massive market penetration across the Asia-Pacific region.
Product Line: Ultra-wideband modems, envelope trackers, diversity modules, and advanced power amplifiers.
2. Broadcom Inc.
Pioneers high-performance film bulk acoustic resonator (FBAR) filter technology for smartphones.
Founded: 1961 | HQ: San Jose, California, USA.
Why It Ranks: Possesses crucial intellectual property rights for premium high-frequency filtering components.
Regional Dominance: Maintains strong supply chain relationships across North American and European markets.
Product Line: Co-packaged optics, FBAR filters, Wi-Fi 7/8 front-end modules, and switches.
3. Skyworks Solutions, Inc.
Acts as a primary component supplier for Apple and premium Android flagships.
Founded: 1962 | HQ: Irvine, California, USA.
Why It Ranks: Recognized as a market pioneer advancing early 6G FR3 infrastructure development.
Regional Dominance: Deeply integrated into the manufacturing supply chains of North American OEMs.
Product Line: Sky5 platforms, power amplifiers, LNA modules, and customized infrastructure tuners.
4. Qorvo, Inc.
Formed by the historic RFMD and TriQuint merger to create massive capacity.
Founded: 2015 | HQ: Greensboro, North Carolina, USA.
Why It Ranks: Serves as a critical hardware supplier for advanced aerospace and defense networks.
Regional Dominance: Strong cross-border footprint spanning major telecommunications hubs in North America and Europe.
Product Line: Bulk Acoustic Wave (BAW) filters, multiplexers, switches, and GaN discrete transistors.
5. Murata Manufacturing Co., Ltd.
Commands the global supply chain for passive electronic components and SAW filters.
Founded: 1944 | HQ: Kyoto, Japan.
Why It Ranks: Controls a vast portfolio of newly granted RFFE technology patent families.
Regional Dominance: Exercises unmatched operational dominance across electronics manufacturers in East Asia.
Product Line: Surface Acoustic Wave (SAW) filters, ceramic capacitors, low-profile duplexers, and RF modules.
6. Infineon Technologies AG
Specializes in supplying highly reliable RF packaging for severe automotive environments.
Founded: 1999 | HQ: Neubiberg, Germany.
Why It Ranks: Leads industrial digitization and green energy power management chip development projects.
Regional Dominance: Heavily anchors the European automotive semiconductor and automated factory industrial sectors.
Product Line: Low-noise amplifiers (LNAs), RF switches, radar sensor chips, and power ICs.
7. TDK Corporation
Acquired Epcos to secure its leading market share in high-performance RF filters.
Founded: 1935 | HQ: Tokyo, Japan.
Why It Ranks: Provides essential surface-mount passive components required for tight smartphone circuit boards.
Regional Dominance: Enjoys structural advantages supplying tier-one consumer electronics brands across East Asia.
Product Line: RF diplexers, thin-film directional couplers, multi-layer bandpass filters, and patch antennas.
8. STMicroelectronics N.V.
Utilizes specialized Silicon-on-Insulator (SOI) wafer fabrication technologies for efficient RF switches.
Founded: 1987 | HQ: Geneva, Switzerland.
Why It Ranks: Key enabler of next-generation cellular IoT and smart infrastructure sensor deployments.
Regional Dominance: Dominates the European smart mobility ecosystem and diversified global industrial accounts.
Product Line: RF-SOI transistors, impedance matching networks, integrated baluns, and high-frequency mixers.
9. NXP Semiconductors N.V.
Integrates localized RF front-ends with massive computing microcontrollers for automotive systems.
Founded: 1953 | HQ: Eindhoven, Netherlands.
Why It Ranks: Unrivaled leader in supplying V2X secure vehicle communication hardware platforms.
Regional Dominance: Heavily integrated across major Western European and American smart automotive manufacturers.
Product Line: Smart power amplifiers, ultra-wideband (UWB) tracking ICs, transceivers, and radar chipsets.
10. Texas Instruments Incorporated
Supplies a massive inventory of analog components supporting diverse industrial connectivity.
Founded: 1930 | HQ: Dallas, Texas, USA.
Why It Ranks: Relied upon for unmatched longevity and structural component reliability across sectors.
Regional Dominance: Holds deep distribution infrastructure across industrial, medical, and defense sectors worldwide.
Product Line: RF synthesizers, downconverters, high-speed operational amplifiers, and integrated transceiver front-ends.
Conclusion
The Radio Frequency Front-End market is undergoing a dramatic shift in architecture with extreme integration and stringent power requirements. Standalone, distinct components are gradually being replaced by very complex, integrated modem-to-antenna modules as the cellular ecosystem is taking a clear step into 5G-Advanced and preparing the early 6G directions. Consolidation continues as leading semiconductor companies continue to use their expansive patent positions to win high-dollar design wins with the smartphone market. In the future, agility in manufacturing, new materials such as Gallium Nitride, and the ability to withstand supply chain risks will be the key competitive elements in this multi-billion-dollar industry.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


