
Jul 03, 2026
By Transpire Insight
Description
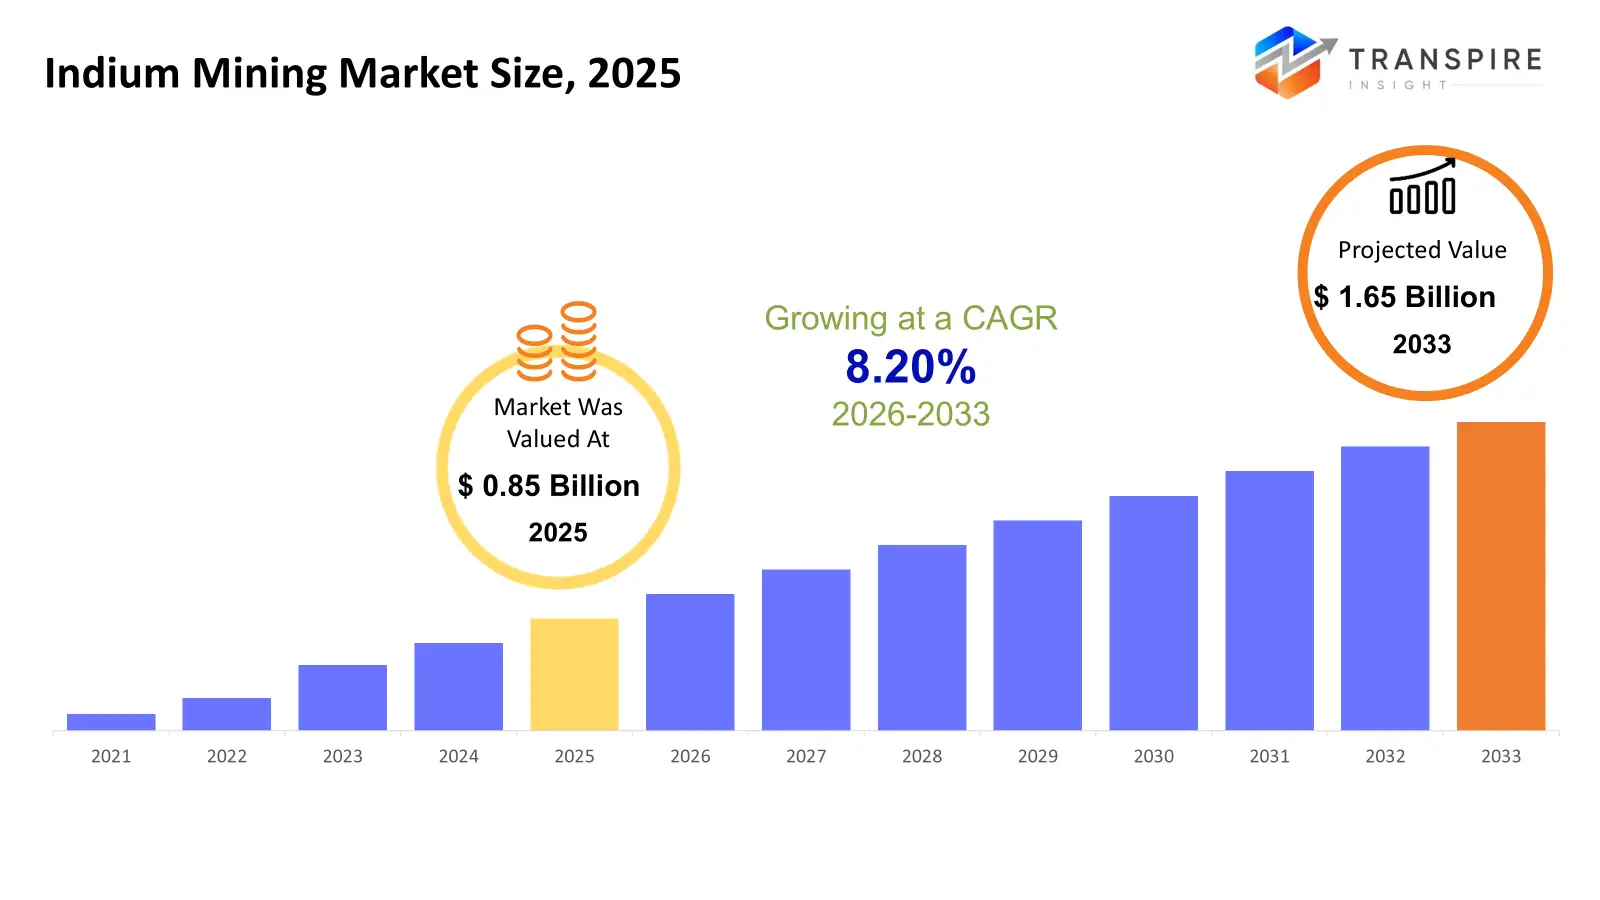
According to a research report published by Transpire Insight, the global indium mining market size is projected to grow from USD 246.4 billion in 2026 to USD 416.5 billion by 2035, at a CAGR of 8.20% during the forecast period 2027-2035. The indium mining market is propelled by skyrocketing demand for Indium Tin Oxide used in consumer electronics displays, coupled with expanding installations of high-efficiency thin-film solar panels and 5G telecommunication networks.
Introduction
The indium mining market encompasses the extraction and refining of a rare, soft metal primarily recovered as a critical byproduct of zinc ore processing. Renowned for its unique post-transition properties, indium is essential for producing transparent conductive coatings, specialized semiconductors, and low-temperature alloys. As a cornerstone material for modern technological infrastructure, the market relies heavily on optimized metallurgical recovery and advanced electronic-waste recycling to meet the evolving demands of high-performance manufacturing sectors.
Recent Development News
March 2026: Flash Metals USA signed a long-term offtake agreement with Indium Corporation to supply critical recovered metals, including indium, harvested directly from domestic US electronics recycling operations.
February 2025: China's Ministry of Commerce implemented stringent new export licensing restrictions on several critical minerals, including unwrought indium compounds, causing global supply contraction and notable price volatility.
Download the exclusive Global Indium Mining Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Indium Mining Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America is expected to experience steady growth during the forecast period in the Indium Mining market. The region maintains a highly strategic position in the Indium Mining Market owing to the presence of advanced semiconductor fabricators, high-tech aerospace technology suppliers, and robust investment in defense electronics. The United States and Canada are critical components of this market, considering factors such as extensive commercial electronic component manufacturing operations, strategic national stockpiling initiatives, and continued advancement in optoelectronic engineering. Canada, in particular, holds significant potential as a major producer of primary indium recovered as a by-product from its zinc and polymetallic mining operations. As of 2025, several exploration projects in British Columbia and Quebec have undertaken specialized production activities aimed at enhancing the recovery efficiency of critical minerals to support the North American supply chain.
Asia Pacific is anticipated to generate the highest demand during the forecast period in the Indium Mining market, holding an overwhelming dominant global revenue share of over 90%. It is expected that the Asia-Pacific region will witness the highest growth rate during the forecast period due to an immense and increasing demand for consumer electronics, massive production of flat-panel displays, expanding thin-film solar cell installations, and significant investment in telecommunication infrastructure. China, Japan, and South Korea are the leading nations regarding commercial electronics activities, driving the bulk of global demand for advanced indium tin oxide (ITO) technologies. In 2025, there has been an increase in production modernization and resource recovery programs by major refiners and smelters across China and South Korea, aiming to protect against supply volatility while ensuring domestic semiconductor self-sufficiency.
Top 15 Trends in the Indium Mining Market
Proceed to Checkout to purchase the exclusive Global Indium Mining Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
1. Rising demand from semiconductor manufacturing industries
Indium is increasingly used in semiconductor components for displays, chips, and optoelectronics. Growing electronics production drives mining expansion, as manufacturers seek a reliable indium supply for advanced technologies and miniaturized devices.
2. Recycling of indium from electronic waste is growing rapidly
Recycling indium from electronic waste is becoming more important due to limited natural reserves. Recovery processes improve supply security while reducing environmental impact and supporting circular economy initiatives worldwide.
3. Supply constraints due to limited primary indium deposits
Indium supply is constrained because primary deposits are rare and geographically concentrated. This creates market vulnerability, price fluctuations, and encourages recycling and alternative sourcing strategies across global industries dependent on.
4. Growing use of touchscreens and LCD panels
Touchscreen and LCD panel manufacturing heavily relies on indium tin oxide coatings. Increasing consumer electronics demand drives higher indium consumption, especially in smartphones, tablets, monitors, and display technologies globally, expanding.
5. Asia-Pacific dominating global indium production and consumption
The Asia-Pacific region dominates global indium production and consumption due to a strong electronics manufacturing base in China, Japan, and South Korea. This concentration enhances supply chains but increases regional dependency risks.
6. Integration of indium into renewable energy technologies
Indium is increasingly integrated into thin-film solar cells and other renewable energy technologies. This supports efficiency improvements while expanding sustainable energy applications, driving long-term demand growth in global markets.
Top 25 Companies Leading the Indium Mining Market
Customize the exclusive Global Indium Mining Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
Leading Indium Mining Companies to Watch Globally
The top 25 companies dominating the indium mining market
Produces eleven percent of the world's indium at its Onsan refinery.
Founded: 1974 | HQ: Seoul, South Korea.
Why It Ranks: World's top primary producer, bypassing Chinese export control supply lines.
Regional Dominance: Dominates South Korea and major high-tech export markets across Asia.
Product Line: Refined indium metal, specialty zinc byproducts, and industrial precious metals.
Recovers high-purity rare metals from electronic waste via advanced recycling.
Founded: 1884 | HQ: Tokyo, Japan.
Why It Ranks: Unrivaled leader in secondary indium reclamation from spent electronic materials.
Regional Dominance: Holds supreme market leadership within the Japanese advanced electronics sector.
Product Line: Indium tin oxide targets, recycled indium metal, and semiconductor substrates.
Refines and fabricates custom indium materials for global technology manufacturers.
Founded: 1934 | HQ: Clinton, New York, United States.
Why It Ranks: Global standard setter for technical expertise and customized chemical formulations.
Regional Dominance: Commands absolute market share across North American microelectronics and defense.
Product Line: Indium solders, thermal interface materials, ribbons, and inorganic indium chemicals.
Processes complex industrial byproducts to extract valuable critical technological minerals.
Founded: 1989 | HQ: Brussels, Belgium.
Why It Ranks: Leading circular economy player specializing in sustainable technology and metal recovery.
Regional Dominance: Sets the standard for green mineral sourcing across European markets.
Product Line: High-purity indium compounds, thin-film materials, and sustainable recycling services.
Extracts significant quantities of primary indium alongside large-scale zinc operations.
Founded: 1913 | HQ: Vancouver, Canada.
Why It Ranks: Top primary critical mineral extractor within the North American continent.
Regional Dominance: Controls substantial zinc-indium supply networks across Canada and America.
Product Line: Indium-bearing zinc concentrates, refined zinc, and specialty co-product metals.
Operates multi-continental smelters recovering critical metals during extensive zinc processing.
Founded: 2007 | HQ: Budel, Netherlands.
Why It Ranks: European smelting giant providing vital raw materials to global electronics.
Regional Dominance: Anchors key non-ferrous metal supply grids throughout the European Union.
Product Line: Crude indium concentrates, refined zinc metal, and essential metal byproducts.
Operates the Sukpo refinery utilizing advanced zinc byproduct recovery systems.
Founded: 1949 | HQ: Seoul, South Korea.
Why It Ranks: Main parent entity reinforcing South Korea’s non-ferrous metallurgical market strength.
Regional Dominance: Exercises highly powerful supply chain control within East Asian industrial sectors.
Product Line: High-grade indium metal, refined zinc slabs, and sulfuric acid chemicals.
Specializes in producing ultra-high purity metals required for critical semiconductors.
Founded: 1957 | HQ: Langelsheim, Germany.
Why It Ranks: Essential boutique supplier for hyper-specific scientific and semiconductor-grade applications.
Regional Dominance: Supplies critical precision tech components directly to Germany’s automotive base.
Product Line: Ultra-purity indium metal, semiconductor compounds, and custom physical shapes.
Controls vast reserves of dispersed rare elements, including commercial-grade indium.
Founded: 2003 | HQ: Lincang, China
Why It Ranks: Dominant state-backed enterprise dictating raw material flow to global markets.
Regional Dominance: Commands vast upstream resource authority within domestic Chinese mining zones.
Product Line: Indium ingots, germanium dioxide, and high-purity rare metal compounds.
Integrates extensive mining assets with high-tech downstream indium material refining.
Founded: 2008 | HQ: Nanning, China.
Why It Ranks: Key industrial hub manufacturing large volumes of transparent conductive materials.
Regional Dominance: Powers have dominant flat-panel display manufacturing centers located inside Mainland China.
Product Line: Indium tin oxide targets, refined indium, and high-purity chemicals.
Schedule a meeting with our market experts to discuss the exclusive Global Indium Mining Market report and identify the best research solution for your organization.
Conclusion
The indium mining market occupies a vital position within the global supply chains of high-tech manufacturing and green energy infrastructure. Propelled by its irreplaceable nature in optoelectronics and renewable energy arrays, the market must continuously adapt to geopolitical trade filters and processing limitations. Future expansion hinges entirely on engineering efficient secondary extraction methods and creating reliable recycling closed loops. Ensuring supply security while maintaining environmental compliance remains the defining benchmark for stakeholders navigating this critical mineral landscape.


Send us a brief description of your challenge and we'll get back to you within 24 hours.
 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


