
Jul 31, 2026
By Transpire Insight
Description
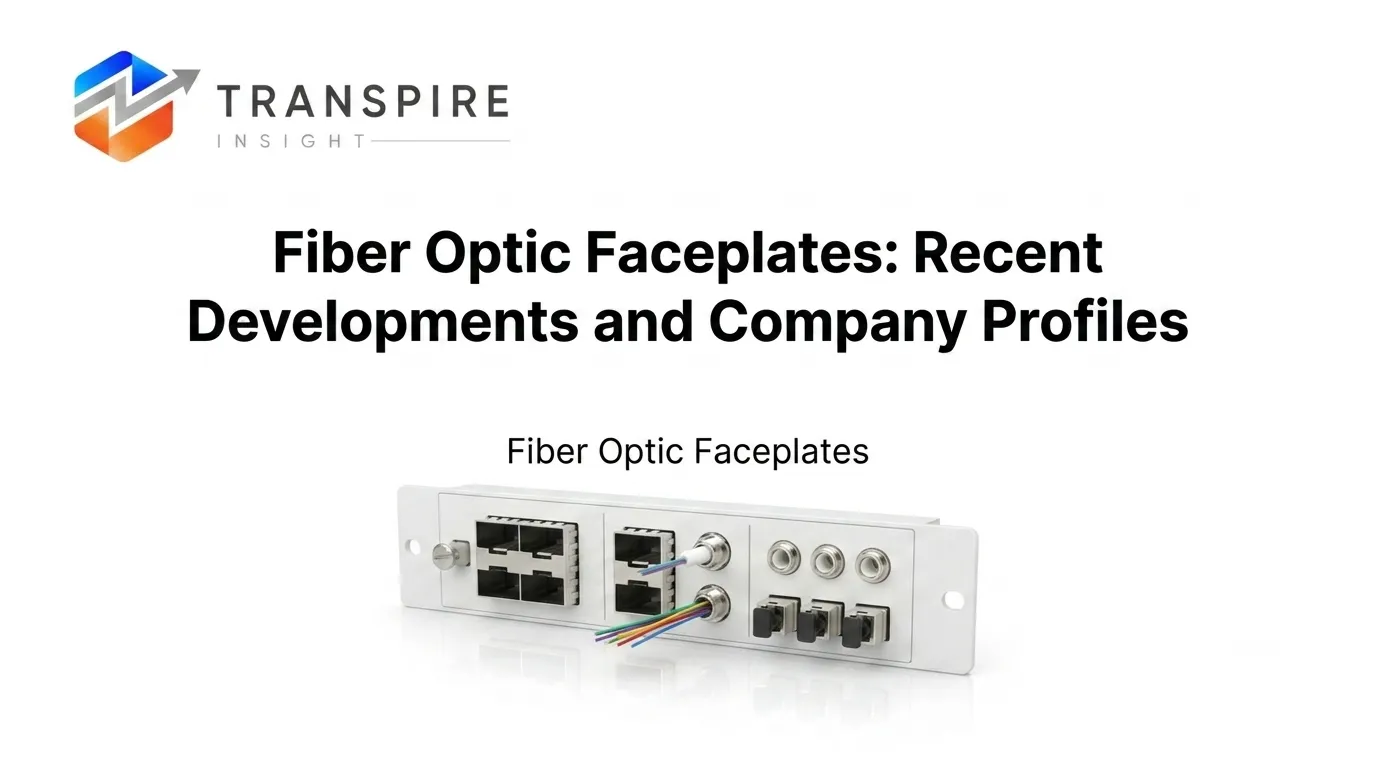
According to a research report published by Transpire Insight, the fiber optic faceplates market size is projected to grow from USD 200.10 million in 2026 to USD 315.22 million by 2035, at a CAGR of 5.01% during the forecast period 2026-2035. Market adoption is heavily accelerated by the rapid worldwide rollout of dense 5G network architectures, massive private corporate investments in hyperscale AI data center facilities, rising global broadband demand, and strict architectural shifts toward clean structured wall cabling.
Introduction
The fiber optic faceplates market is growing at a fast pace on a global scale, as the digital infrastructure landscape is rapidly changing. These specialized elements play a crucial role in next-generation networking and advanced imaging, maintaining clean and distortion-free signal transmission and facilitating smooth device connectivity. With ever-expanding data center infrastructure, ever-increasing bandwidth of 5G backhaul solutions, and ever-growing FTTH (Fiber-To-The-Home) deployments, operators must rely on highly modular and rugged wall termination equipment, which will help ensure a streamlined, long-term physical layer organization and prevent complex fiber splices from being damaged by harsh environmental conditions.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Fiber Optic Faceplates Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Fiber Optic Faceplates Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America's leadership is anchored in its strong legacy in defense, medical imaging, and night vision industries. The trend of replacing legacy CCD-based imaging sensors with fiber-coupled digital detectors is still in progress in hospitals around the region, as a growing number of hospitals strive to meet tightening radiation safety standards, which demand even more rapid plate replacement cycles. The defense and aerospace industry has been a steady consumer of the highly mature established players like Schott and Incom, which are known for their minimally invasive surgical equipment, endoscopy systems, and image-intensifier tubes. Despite relatively moderate growth, North America continues to be the anchor market, drawing companies with strong or substantial defense modernization budgets and major night-vision and optoelectronics manufacturers.
The growth in Asia-Pacific is attributed to the precision optics manufacturing capabilities as well as the rapid growth in healthcare facilities. Japan continues to be a technological leader, with Hamamatsu Photonics and AGC, for instance, dominant in high-precision optics areas that serve domestic OEMs and provide export products for medical and scientific imaging. As China, India and South Korea invest in their own telecommunications, defence modernization, and hospital infrastructure, the scope for faceplates to be employed in image intensifiers, X-ray detectors and inspection systems for industry is broadening. The Asia-Pacific region is currently the most promising, long-term growth driver for the market, with a growing number of research institutions and scientific instrumentation projects in the region.
Top 15 Trends in the Fiber Optic Faceplates Market
Proceed to Checkout to purchase the exclusive Fiber Optic Faceplates Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
Replacement of CCD Sensors with Fiber-Coupled Detectors
Hospitals are phasing out legacy CCD-based imaging sensors in favor of fiber-coupled digital detectors, which deliver sharper resolution, lower distortion, and improved diagnostic image clarity.
Expansion of Night-Vision Device Manufacturing
Defense agencies worldwide are scaling procurement of night-vision goggles and image-intensifier tubes, driving steady faceplate demand from manufacturers serving military, aerospace, and homeland-security imaging applications.
Increasing Adoption in X-ray and Radiography Systems
Fiber optic faceplates are increasingly integrated into digital X-ray and radiography detectors, enabling compact, lightweight designs while preserving spatial image accuracy for diagnostic and industrial use.
Rising Investment in Precision Optics Manufacturing Hubs
Companies like Hamamatsu and AGC are expanding precision optics clusters in Japan, strengthening regional manufacturing capacity to serve growing domestic and export demand for imaging components.
Tightening Radiation-Safety Standards Accelerating Plate Replacement
Stricter regulatory standards governing diagnostic radiation exposure are pushing healthcare networks to retire older imaging plates faster, accelerating replacement cycles and boosting recurring faceplate demand.
Expansion of Healthcare Infrastructure Across Asia-Pacific
Widely expanding hospital networks in these countries, China, India, and South Korea, are growing installations of fiber-coupled imaging devices, further driving the addressable faceplate component market. This is due to the widespread growth of hospital networks in these countries, which are driving the addressable faceplate component market.
List of Top 25 Companies Leading the Fiber Optic Faceplates Market
Customize the exclusive Fiber Optic Faceplates Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. CommScope Holding Company, Inc.
Multi-billion-dollar networking titan designing premier structured cabling architectural hardware portfolios globally.
Founded: 1976 | HQ: North Carolina, USA.
Why It Ranks: Unrivaled market authority in commercial-grade enterprise and institutional workspace termination plates.
Regional Dominance: Holds leading structural consumer market share across the North American continent.
Product Line: Propel modular panels, high-density wall outlets, and dynamic workplace faceplates.
2. Corning Incorporated
Glass science pioneer establishing fundamental baseline standards for low-attenuation optical transmission.
Founded: 1851 | HQ: New York, USA.
Why It Ranks: Globally revered for premium manufacturing, durability, and precision end-to-end cable solutions.
Regional Dominance: Massive infrastructure presence spanning North America, European networks, and Asia-Pacific.
Product Line: ClearCurve bend-insensitive fibers, high-capacity hardware boxes, and industrial-grade outlet plates.
3. Legrand S.A.
Global building infrastructure specialist designing beautifully integrated high-performance electrical wiring controls.
Founded: 1865 | HQ: Limoges, France.
Why It Ranks: Top-tier producer of modular, aesthetically versatile architectural low-voltage faceplate fixtures.
Regional Dominance: Enjoys structural dominance throughout residential and commercial building markets across Europe.
Product Line: Ortronics structural network outlets, customizable multimedia faceplates, and workstation boxes.
4. Panduit Corp.
Industrial engineering innovator providing physically robust end-to-end data center hardware configurations.
Founded: 1955 | HQ: Illinois, USA.
Why It Ranks: Preeminent provider of durable, highly customizable modular workspace network outlets.
Regional Dominance: Extremely deep commercial enterprise contract penetration within the North American sector.
Product Line: Mini-Com modular flush-mount faceplates, network outlet frames, and patch cord organizers.
5. Schneider Electric SE
Energy management superpower prioritizing smart, highly sustainable green connectivity network infrastructure.
Founded: 1836 | HQ: Rueil-Malmaison, France.
Why It Ranks: Outstanding global integration combining premium aesthetic styles with tough mechanical protection.
Regional Dominance: Powerful industrial market presence distributed across European and Middle Eastern grids.
Product Line: Actassi integrated structural data jacks, modular wall plates, and utility enclosures.
6. Hubbell Incorporated
Heavy-duty supplier manufacturing ultra-ruggedized components built for severe industrial applications.
Founded: 1888 | HQ: Connecticut, USA.
Why It Ranks: Premier provider of high-impact, chemical-resistant connectivity housings for hazardous operating zones.
Regional Dominance: Well entrenched as a core hardware supplier across heavy industrial USA.
Product Line: Nextframe performance plate kits, stainless steel industrial plates, and surface boxes.
7. Molex, LLC
Advanced electronic component specialist delivering ultra-precise micro-connectivity options to diverse industries.
Founded: 1938 | HQ: Illinois, USA.
Why It Ranks: Highly trusted by telecom operators for specialized, high-density fiber routing layouts.
Regional Dominance: Strongly positioned across multi-national electronic hardware manufacturing networks in Asia-Pacific.
Product Line: Synergy clean-profile wall outlets, fiber adapters, and high-density termination frames.
8. Leviton Manufacturing Co., Inc.
Electrical giant pioneering quick-install modular systems for complex modern building configurations.
Founded: 1906 | HQ: New York, USA.
Why It Ranks: Sets the standard for versatile, tool-free snap-in multimedia workspace connection modules.
Regional Dominance: Massive, ubiquitous retail and distributor network footprint throughout civilian North America.
Product Line: QuickPort modular faceplates, structured media center housings, and fiber adapters.
9. HellermannTyton
Cable management expert focused on creating highly efficient commercial routing solutions.
Founded: 1933 | HQ: Tornesch, Germany.
Why It Ranks: Highly favored by installation teams for intuitive, time-saving cable routing designs.
Regional Dominance: Excellent market penetration throughout European telecom distribution and installation networks.
Product Line: Alpha modular wall faceplates, category-rated patch fields, and protective conduits.
10. Siemon Company
Century-old telecommunications authority dedicating its research exclusively to elite structured cabling.
Founded: 1903 | HQ: Connecticut, USA.
Why It Ranks: Recognized by global experts for bulletproof reliability and premium shielding designs.
Regional Dominance: Commands substantial institutional market loyalty globally, with strong European corporate ties.
Product Line: MAX modular angled faceplates, heavy-duty network work area outlets, and adaptors.
Schedule a meeting with our market experts to discuss the exclusive Fiber Optic Faceplates Market report and identify the best research solution for your organization.
Conclusion
The fiber optic faceplates market is navigating an unprecedented structural upgrade cycle. As major global enterprise networks expand hyperscale AI data centers and roll out fiber connections to remote locations, the requirement for robust termination hardware will remain critical. By embedding smarter tracking labels and implementing quick-install angled jacks that minimize signal bend loss, these leading market suppliers are optimally positioned to support the massive broadband demand shaping the global landscape.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


