
Jul 15, 2026
By Transpire Insight
Description
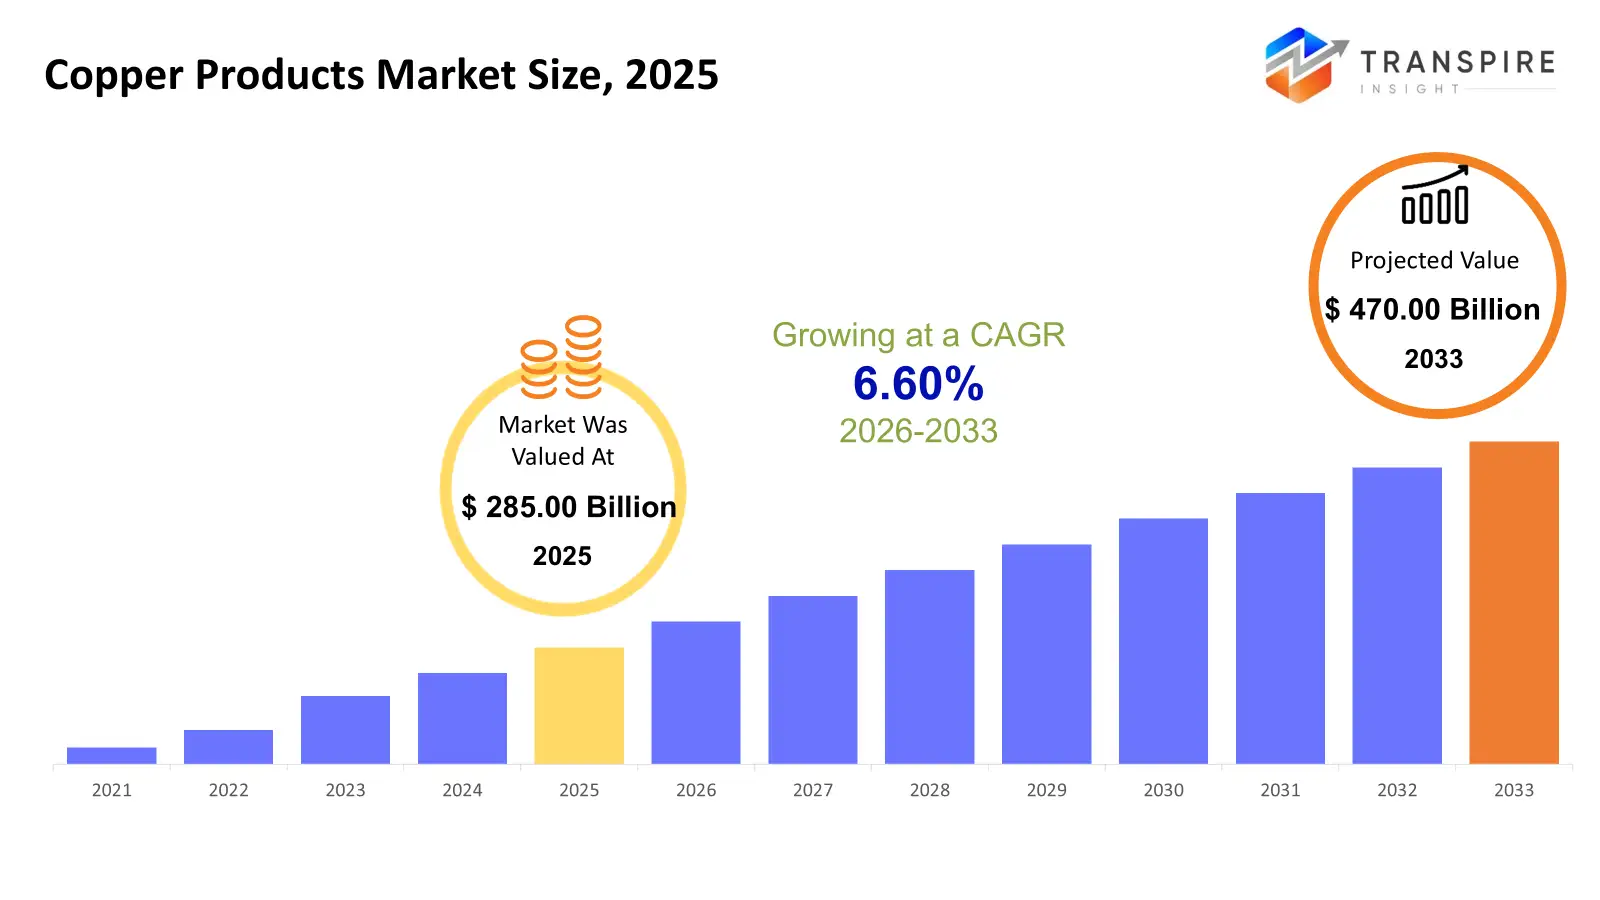
According to a research report published by Transpire Insight, the global copper products market size is projected to grow from USD 384.43 billion in 2026 to USD 745.67 billion by 2035, at a CAGR of 9.20% during the forecast period 2026-2035. The key drivers are the acceleration in global electrification, large investments in AI data centres, and the growth of renewable energy infrastructure. Furthermore, the growing electric vehicle industry and grid modernization projects are dramatically increasing demand in the face of constricting worldwide structural supply shortages.
Introduction
The copper products market is an essential backbone for modern business growth and infrastructure development across the globe. Copper, which has high electrical and thermal conductivity, durability, and is completely recyclable, is converted to a range of high-value downstream products such as wire rods, tubes, sheets and plates, as well as specialty alloys. At the moment, the global economy is turning towards massive sustainability objectives and digital transformation, the market is moving from a cyclical industrial commodity to a very strategic technological resource. Demands are increasing from high-tech applications, pushing the dynamics and processing capacities of the global supply chain.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Copper Products Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Copper Products Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
North America is expected to remain the dominant region during the forecast period in the copper products market. The dominant position of North America is supported by grid modernization, renewable energy build-out, and electric vehicle charging point investments, alongside domestic manufacturing and energy-efficiency regulatory themes that keep copper demand structurally stable. The United States is currently the largest contributor to regional demand, driven by infrastructure programs, semiconductor fabrication facility construction, and rapid EV market growth, all of which push high consumption of copper wires, foils, and transformer materials. In 2026, Aurubis AG, Europe's leading copper producer, made a major strategic move into the U.S. market with a USD 800 million investment in a copper recycling facility in Richmond, Georgia, a signal of how recycling capacity is becoming central to North American supply security alongside primary demand growth.
Asia-Pacific is anticipated to witness rapid growth during the forecast period in the copper products market. This growth is driven by fast urbanization and industrialization in China and India, alongside expanding renewable energy installations and electric vehicle adoption that are increasing copper intensity per unit of infrastructure. China alone accounts for nearly half of the world's demand for refined copper, owing to its vast manufacturing base and booming construction industry. Large-scale infrastructure initiatives, such as India's Smart Cities Mission and China's Belt and Road Initiative, are further driving up demand for copper in smart grid systems, electricity distribution, and construction, cementing the region's role as both a manufacturing hub and a consumption powerhouse.
Top 15 Trends in the Copper Products Market
Proceed to Checkout to purchase the exclusive Copper Products Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
List of 25 Companies Leading the Copper Products Market To Watch Globally
Customize the exclusive Copper Products Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
The Top 25 Companies Leading the Copper Products Market
1. Aurubis AG
It is the largest copper recycler worldwide and a leading multimetal producer.
Founded: 1866 | HQ: Hamburg, Germany.
Why It Ranks: Commands the European market through massive secondary copper recycling and cathode production.
Regional Dominance: Highly dominant across the European continent, with an expanding global footprint.
GuruFocus
Product Line: Copper cathodes, wire rods, continuous cast shapes, profiles, and rolled products.
2. Jiangxi Copper Corporation
Operates the largest open-pit copper mine in mainland China, at Dexing.
Founded: 1979 | HQ: Guixi, China.
Why It Ranks: It is China's largest integrated copper producer by total output volume.
Mining.com
Regional Dominance: Massive, uncontested structural dominance across China and broader Asian industrial sectors.
Product Line: Copper cathodes, wire rods, copper foils, sheets, anodes, and tubes.
3. KME Group SpA
A key European powerhouse focusing strictly on downstream copper alloy processing.
Founded: 1886 | HQ: Florence, Italy.
Why It Ranks: Leads architectural and industrial copper product engineering across Western European nations.
Regional Dominance: Strong manufacturing and commercial footprint across Italy, Germany, and France.
Product Line: Copper tubes, rolled bars, industrial strips, and maritime copper-nickel alloys.
4. Wieland-Werke AG
Specializes in high-precision, custom-engineered copper alloy solutions for global technology sectors.
Founded: 1820 | HQ: Ulm, Germany.
Why It Ranks: Recognized globally for premium-tier technological innovation in semi-finished copper items.
Regional Dominance: Strong manufacturing base in Europe alongside rapidly expanding North American installations.
Product Line: Precision strips, sheets, wires, tubes, busbars, and engineered slide bearings.
5. Mueller Industries Inc.
The premier supplier of copper piping networks to North American distributors.
Founded: 1917 | HQ: Collierville, Tennessee, USA.
Why It Ranks: Holds the most significant market share for plumbing copper components domestically.
Regional Dominance: Enjoys ultimate market penetration throughout the United States, Canada, and Mexico.
Product Line: Copper tubes, fittings, valves, line sets, and brass rod extrusions.
6. Hailiang Group Co., Ltd.
One of the world's absolute largest manufacturers of copper tubing products.
Founded: 1989 | HQ: Hangzhou, China.
Why It Ranks: Massive production scale yields unmatched cost efficiencies in global plumbing components.
Regional Dominance: Global export dominance across Asia, North America, Europe, and the Middle East.
Product Line: Copper pipes, fittings, HVAC coils, and specialized copper-alloy heat exchangers.
7. Ningbo Jintian Copper (Group) Co., Ltd.
Highly regarded for high-volume processing of recycled scrap copper in processing lines.
Founded: 1986 | HQ: Ningbo, China.
Why It Ranks: Ranks top-tier in total processed volume of diverse copper processing formats.
Regional Dominance: Possesses comprehensive commercial supply network penetration across industrial manufacturing hubs globally.
Product Line: Copper wires, rods, plates, strips, tubes, and neodymium permanent magnets.
8. Mitsubishi Materials Corporation
Integrates advanced metallurgy into electronics, providing high-purity copper processing materials.
Founded: 1871 | HQ: Tokyo, Japan.
Why It Ranks: Pioneer of ultra-clean oxygen-free copper varieties vital for advanced semiconductors.
Regional Dominance: Highly influential within Japan and advanced tech assembly markets across Asia.
Product Line: High-purity copper anodes, continuous-cast rods, sheets, and oxygen-free products.
9. Furukawa Electric Co., Ltd.
Focuses on infrastructure-grade copper products for telecom and green automotive cabling.
Founded: 1884 | HQ: Tokyo, Japan.
Why It Ranks: Vital supplier of high-performance copper foils required in modern EV batteries.
Regional Dominance: Strong market leadership spanning Japan, Southeast Asia, and international electronics grids.
Product Line: Electrodeposited copper foils, high-voltage cables, memory wires, and customized connectors.
10. Poongsan Corporation
South Korea's premier supplier of fabricated copper products and military munitions.
Founded: 1968 | HQ: Seoul, South Korea.
Why It Ranks: Major global exporter of high-grade coin blanks and industrial copper strips.
Regional Dominance: Deeply rooted in South Korea with highly successful, expansive American distribution subsidiaries.
Product Line: Copper plates, strips, sheets, rods, wires, coin blanks, and ammunition.
Schedule a meeting with our market experts to discuss the exclusive Copper Products Market report and identify the best research solution for your organization.
Conclusion
The copper products sales are fundamentally changing from an industrial commodity business to a vital, strategic base for the world's green energy transition and digital future. But demand remains outstripping the capabilities of the mines, as driven by unavoidable macro trends, such as artificial intelligence infrastructure, electric vehicle rollouts and renewable integration. The top 10 leading companies are proactively investing in recycling, developing new technologies, and establishing local and regional growth to address these structural challenges and ensure supply security.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


