
Jul 30, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the aerospace fluoropolymers market size is projected to grow from USD 846.2 million in 2026 to USD 976.22 million by 2035, at a CAGR of 5.22% during the forecast period 2026-2035.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Aerospace Fluoropolymers Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Aerospace Fluoropolymers Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America is a leader in the production of major aircraft OEMs and defense firms, and has a strong focus on government spending on military and space programs. AIRLINES' fleet growth is the minimum demand driver, as with Alaska Airlines' order for 52 Boeing 737 MAXs on its way to becoming an all-Boeing mainline fleet, it is a type of ramp-up that directly boosts consumption of fluoropolymer seals, wire insulation, and fuel-system components. Even more demanding FAA safety and performance specifications drive higher purity grades of PTFE, PFA and FKM resins for use in extreme temperatures, specialty fuels and repeated engine vibration, maintaining North America as the key source of revenue while other growth areas are catching up.
The growth in Asia-Pacific is being fuelled by the growth in domestic air traffic, the expansion of China and India's aircraft fleets, as well as increasing regional manufacturing capabilities. The expansion of the production capacity of resins at Arkema's Changshu, China facility, by 35%, is an example of the global resin producers' efforts to localize their resources to meet the demand from the region's expanding commercial and military aviation industry, not just relying on imports. The region's military expenditure growth, such as the next generation of stealth fighters, is continuing to drive momentum, while the cost of labour and government incentives for aerospace investment in the region are providing the region with a structural cost advantage that is projected to maintain the region as the fastest-growing market in the forecast period.
Top 15 Trends in the Aerospace Fluoropolymers Market
Proceed to Checkout to purchase the exclusive Aerospace Fluoropolymers Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
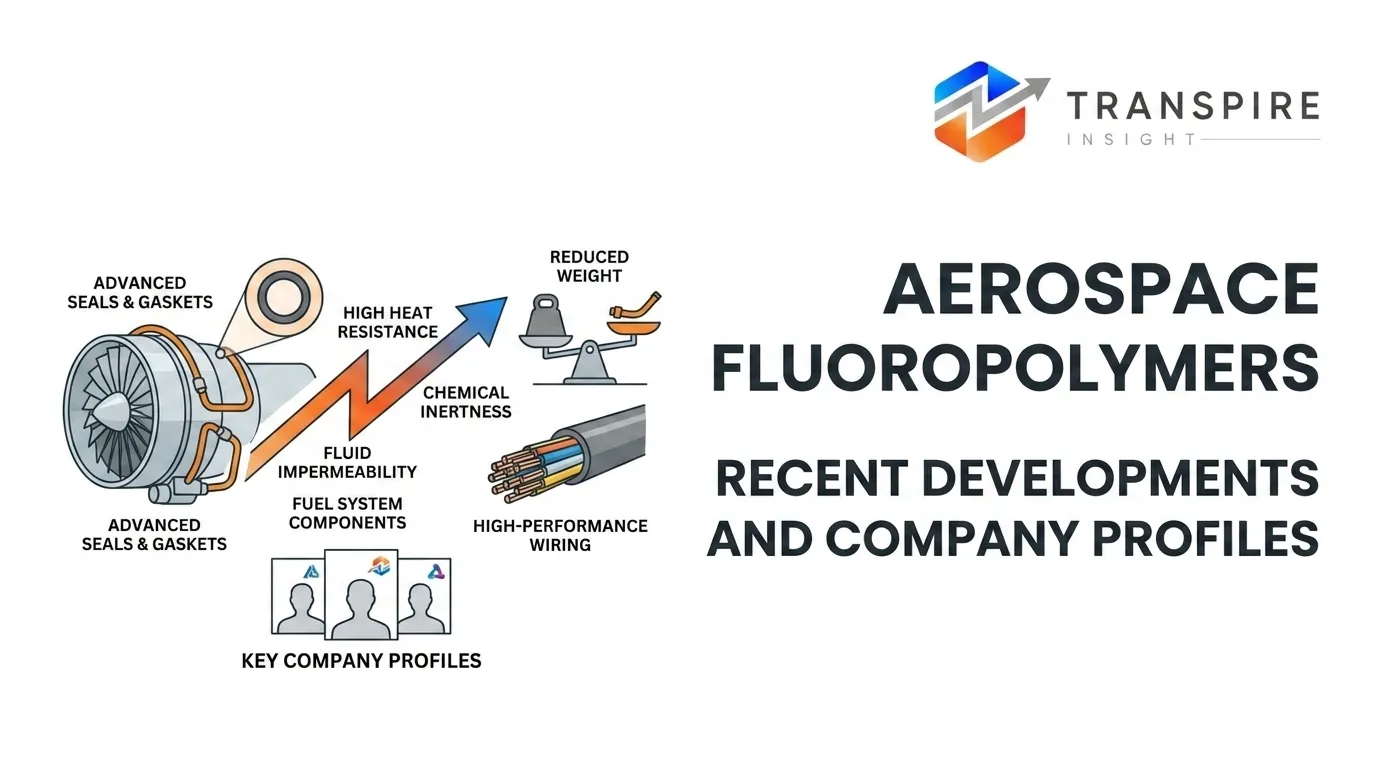
Airlines and OEMs are replacing heavier metal components with fluoropolymer-based parts to cut aircraft weight, lower fuel burn, and reduce emissions across commercial fleets worldwide.
Boeing and Airbus are continuing to accelerate production and orders of new-generation, fuel-efficient commercial aircraft, directly driving up consumption of fluoropolymer in seals, wiring, hoses, and coatings.
The steady growth of the aircraft engine and hydraulic systems market with seals and gaskets is being propelled by exposure to extreme heat, chemicals, and pressure.
China is growing aircraft production, and producers such as Arkema are adding capacity to their fluoropolymer production line, and provide growing cost advantage over existing supply chains.
The new programs of electric and hybrid-electric aircraft need insulation and thermal-management materials that can safely operate under the high-voltage wiring, battery systems, and tight-space, high-load environments of the motor.
Increased military aviation budgets, including next-generation fighter and stealth aircraft programs, are driving demand for high-performance fluoropolymer components able to withstand extreme combat operating environments.
List of Top 25 Companies Leading the Aerospace Fluoropolymers Market
Customize the exclusive Aerospace Fluoropolymers Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Daikin Industries, Ltd.
Pioneer of highly specialized, durable fluorochemical solutions for extreme flight environments.
Founded: 1924 | HQ: Osaka, Japan.
Why It Ranks: Holds massive global patent strength in specialized aerospace fuel system elastomers.
Regional Dominance: Dominates the Asia-Pacific supply network while expanding heavily into Western markets.
Product Line: Polyflon PTFE, Neoflon FEP, and fluoroelastomers for extreme aviation environments.
2. The Chemours Company
Legacy creator of Teflon, defining high-performance industrial chemical standards for decades.
Founded: 2015 | HQ: Delaware, USA.
Why It Ranks: Unmatched historical legacy and global brand recognition in critical electrical shielding.
Regional Dominance: Holds leading structural market share across North American commercial aviation lines.
Product Line: Teflon PTFE, FEP, PFA resins, and Krytox performance aerospace lubricants.
3. AGC Inc.
Diversified glass and chemical giant producing ultra-reliable high-purity fluoropolymer film solutions.
Founded: 1907 | HQ: Tokyo, Japan.
Why It Ranks: Top-tier producer of lightweight, high-dielectric ETFE materials for complex wiring.
Regional Dominance: Strongest structural dominance across the Asian electronic and aerospace manufacturing corridors.
Product Line: Fluon PTFE, Fluon ETFE resins, and specialized high-performance protective films.
4. Arkema S.A.
Advanced material innovator rapidly expanding its global high-performance PVDF manufacturing capacity.
Founded: 2004 | HQ: Colombes, France.
Why It Ranks: Unrivaled technical leadership in ultra-pure, lightweight structural fluoropolymer resin formulations.
Regional Dominance: Commands an extensive distribution network across European aviation and aerospace sectors.
Product Line: Kynar PVDF resins, high-performance coatings, and advanced lightweight structural polymers.
5. Solvay SA
Scientific pioneer offering advanced specialty polymers for mission-critical civilian space exploration.
Founded: 1863 | HQ: Brussels, Belgium.
Why It Ranks: Top global supplier of specialty-grade fluoroelastomers for extreme-temperature engine seals.
Regional Dominance: Maintains highly integrated, deep commercial partnerships throughout European aerospace networks.
Product Line: Tecnoflon FKM, Solef PVDF, and structural aerospace compound sealing materials.
6. 3M Company
Industrial innovation giant engineering highly durable, specialized fluoroplastic structural materials.
Founded: 1902 | HQ: Minnesota, USA.
Why It Ranks: Renowned for high-performance fluoropolymer lines targeting aircraft maintenance and shielding.
Regional Dominance: Entrenched as a primary, trusted supplier across defense aerospace projects.
Product Line: Dyneon PTFE, FEP, PFA materials, and specialized aerospace sealing tapes.
7. Saint-Gobain S.A.
Global materials giant manufacturing ultra-high-precision fluoropolymer bearings, seals, and tubings.
Founded: 1665 | HQ: Courbevoie, France.
Why It Ranks: Unmatched authority in engineering complex, fluid-handling components for commercial jetliners.
Regional Dominance: Deeply integrated into both European and North American aircraft production lines.
Product Line: OmniSeal fluoropolymer seals, specialized aerospace tubing, and low-friction structural bearings.
8. HaloPolymer Holding
One of the largest global producers of bulk polytetrafluoroethylene resins.
Founded: 2008 | HQ: Moscow, Russia.
Why It Ranks: Major independent volume exporter of cost-effective base fluoropolymer raw materials.
Regional Dominance: Possesses significant market distribution footprints across Eastern Europe and Asian markets.
Product Line: Bulk PTFE resins, fluoroplastics, and specialized chemical processing industrial fluids.
9. Polyflon Technology Limited
Specialist precision processor extruding custom components for complex aerospace sub-assemblies.
Founded: 1989 | HQ: Staffordshire, UK.
Why It Ranks: Highly agile custom partner specialized in low-volume, high-complexity precision component machining.
Regional Dominance: Maintains a highly dedicated, professional customer base throughout the UK.
Product Line: Custom machined PTFE parts, thin-walled thermoformed tubing, and electrical insulations.
10. Parker Hannifin Corp.
Global leader in motion and control technologies, engineering advanced sealing systems.
Founded: 1917 | HQ: Ohio, USA.
Why It Ranks: Preeminent Tier-1 integrator combining fluoropolymer science directly into complete flight systems.
Regional Dominance: Extensive and unchallenged delivery network spanning global commercial and military fleets.
Product Line: Fluoropolymer hydraulic seals, extreme-environment O-rings, and braided fuel line hoses.
Schedule a meeting with our market experts to discuss the exclusive Aerospace Fluoropolymers Market report and identify the best research solution for your organization.
Conclusion
The aerospace fluoropolymers market is undergoing a paradigm shift, with stringent emissions regulations and ambitious lightweighting initiatives driving the industry. The global aviation and defense industry will continue to depend on the use of these uniquely chemical- and thermal-resistant materials as their applications are further defined within the growing regulatory environment. Backed by rapid innovations in high-purity processing and scalable recycling tech, these leading global manufacturers are uniquely equipped to supply the highly secure, ultra-durable component pipeline necessary to support the next generation of eco-efficient flight architectures.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


