
United Kingdom uPVC Windows and Doors Market Size & Forecast:
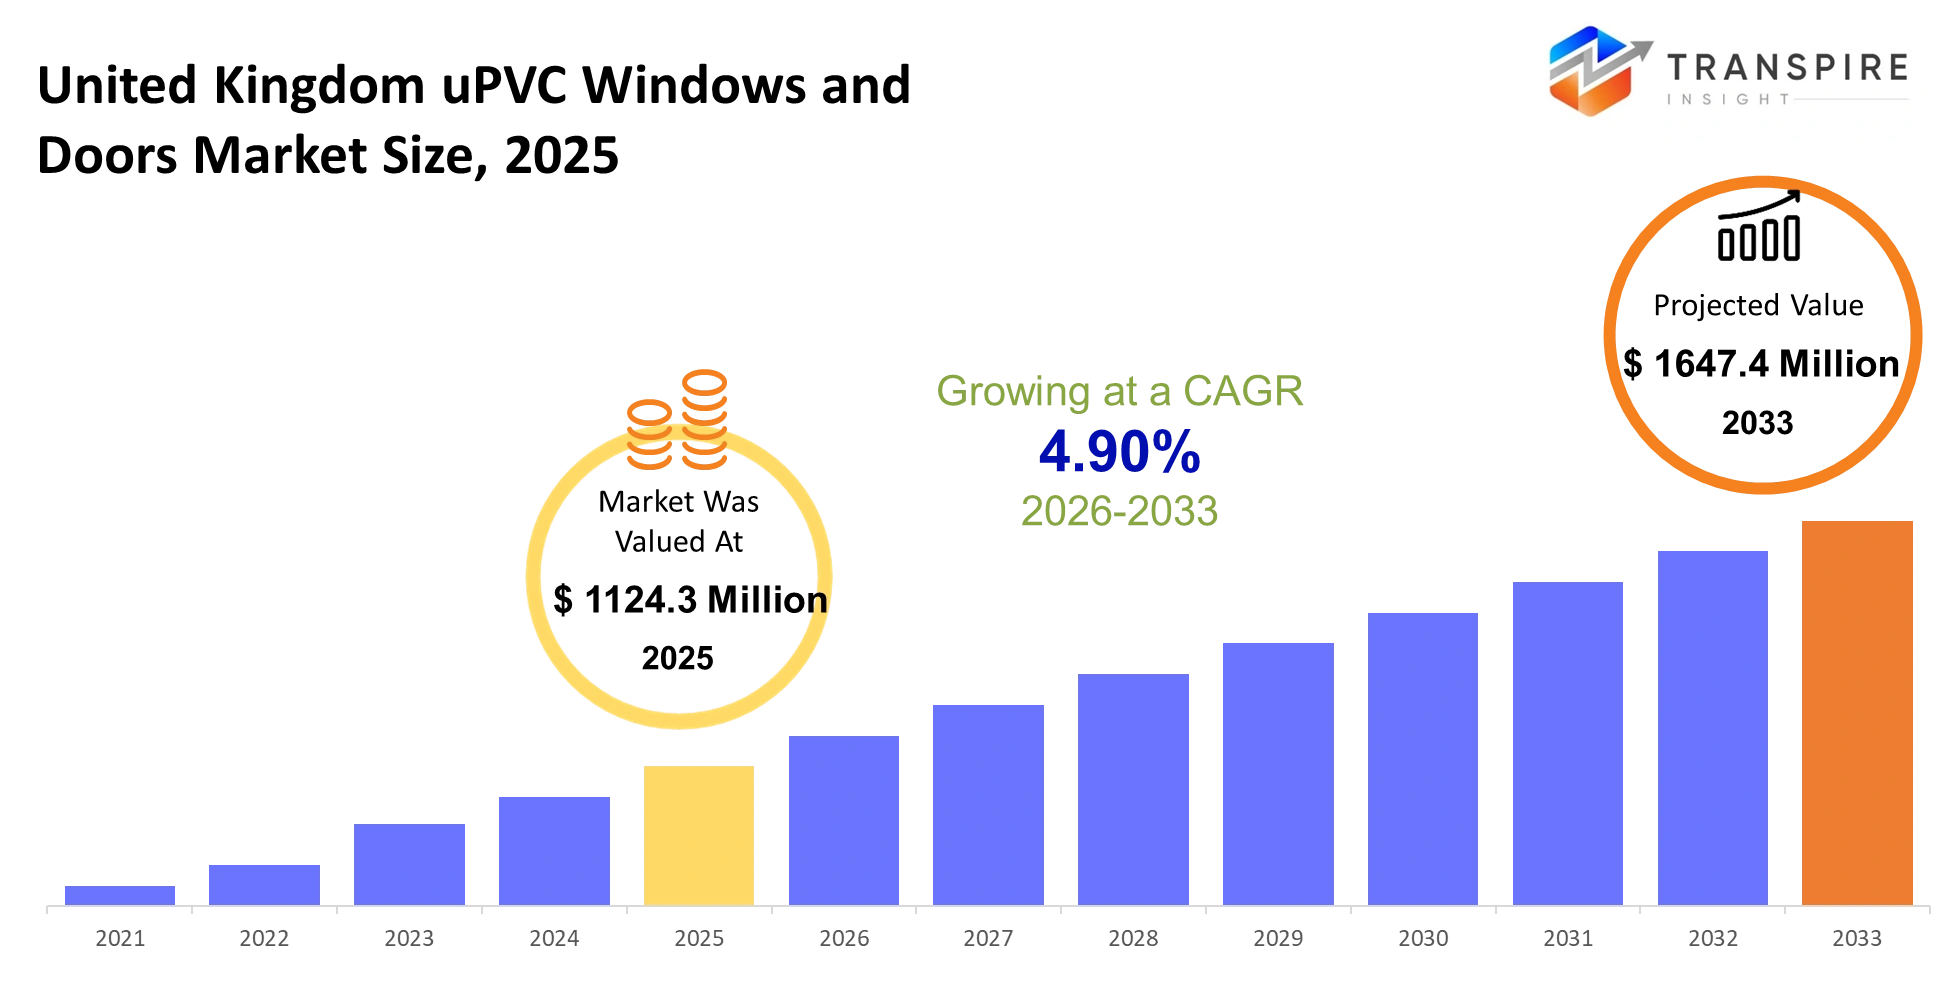
- United Kingdom uPVC Windows and Doors Market Size 2025: USD 1124.3 Million
- United Kingdom uPVC Windows and Doors Market Size 2033: USD 1647.4 Million
- United Kingdom uPVC Windows and Doors Market CAGR:4.90%
- United Kingdom uPVC Windows and Doors Market Segments: By Product Type (uPVC Windows, uPVC Doors, Sliding Doors, Casement Windows, French Doors, Tilt & Turn Windows, Bi-fold Doors, Others); By Application (Residential Buildings, Commercial Buildings, Industrial Buildings, Renovation Projects, Smart Homes, Others); By Glass Type (Double-glazed Windows, Triple-glazed Windows, Laminated Glass, Tempered Glass, Others); By Distribution Channel (Direct Sales, Dealers & Distributors, Online Retail, Specialty Stores, Others)
To learn more about this report,  Download Free Sample Report
United Kingdom uPVC Windows and Doors Market Summary
The United Kingdom uPVC Windows and Doors Market was valued at USD 1124.3 Million in 2025. It is forecast to reach USD 1647.4 Million by 2033. That is a CAGR of 4.90% over the period.
The United Kingdom uPVC Windows and Doors Market takes a kind key part in making homes and offices work better, because heat loss goes down, maintenance ends up lower, and the whole thing holds up longer against the weather across the country’s older building stock. Builders, housing associations and retrofit contractors are turning to uPVC systems more and more, since these options give insulation performance without the ongoing upkeep people often see with timber or metal frames. In the past five years, the market basically moved from only swapping out worn units toward energy-smart retrofit installations, and these align with tighter UK building rules and the net-zero housing goals.
The big 2022 energy price surge kinda nudged homeowners toward spending on insulation improvements, which then really supported demand for high-performance glazing, and also for multi-chamber uPVC profiles. At the same time supply chain disruptions plus resin price swings caused pressure on manufacturers at first, but it also encouraged firms to blend in recycled material and use more localized production approaches. Now, as retrofit work grows across social housing and renovation schemes, manufacturers are landing more valuable orders via premium thermal-performance products, and they’re also offering customized installation solutions.
Key Market Insights
- England pretty much dominated the United Kingdom uPVC Windows and Doors Market , with an estimated 68% share in 2025, mainly because renovation activity stayed really concentrated in housing.
- Scotland is coming up as the quickest moving regional market through 2033, kind of pushed along by public housing retrofit funding , and also stricter insulation compliance targets that keep tightening over time.
- In 2025 , windows took the biggest product slice because the replacement cycles stayed stronger inside older, residential housing stock that’s basically aging out.
- Doors, on the other hand , show the fastest growth , as homeowners increasingly switch toward composite uPVC hybrid entrance systems , for both thermal comfort and security performance, you know.
- Residential use cases captured more than 72% of the market share in 2025, because retrofit demand sped up across semi-detached and terraced housing projects .
- Commercial renovation work is also ticking forward after 2023, since offices, schools, and healthcare facilities keep prioritizing energy-efficiency compliance upgrades.
- Housing associations became a rapidly growing end user category after UK decarbonization funding increased, specifically for social housing insulation modernization projects.
- Brands like VEKA, Rehau, Eurocell, Deceuninck, and Epwin Group are working to lock in market share using recycled-content profiles and more premium glazing technologies .
- Manufacturers have been embedding recycled PVC content between 2023 and 2026 , partly to blunt resin price volatility and to lift their sustainability credentials a bit .
- Smart fabrication technologies and automated profile cutting systems helped cut production waste, while also improving installation turnaround times across UK manufacturing sites.
- Finally, strategic acquisitions picked up after 2025, and Eurocell’s Alunet acquisition is set to boost aluminum and hybrid-system capabilities.
What are the Key Drivers, Restraints, and Opportunities in the United Kingdom uPVC Windows and Doors Market?
The main thing driving the United Kingdom uPVC Windows and Doors Market is the UK building-efficiency rules tightening up, along with higher home energy costs after 2022. Lately, homeowners and property managers have been swapping out older timber and aluminum frames for multi-chamber uPVC setups. The whole idea is to shrink heating losses, and also to meet the newer insulation benchmarks that keep getting updated. This change then boosts revenue chances for manufacturers that sell triple glazing, recycled-profile systems, and more premium thermal insulation products. On top of that, social housing retrofit programs and government-backed decarbonization pushes are also speeding up installation work across big residential portfolios, sort of like a steady wave.
The biggest brake though is the persistent structural weakness in UK new-build housing activity, plus that wider macroeconomic uncertainty vibe that never fully goes away. Interest rates stay higher, construction financing feels tighter and the raw material prices keep being unstable, so residential development plans often get pushed back. These issues can’t get fixed fast, because they rely on a longer economic recovery cycle and housing market stabilization. Because of that, manufacturers are seeing uneven order volumes and margin pressure. This is especially true in the lower-cost product segments where competition is harsher.
Meanwhile a solid opportunity is starting to appear, mainly through deep-retrofit renovation programs aimed at older homes across Northern England and Scotland. Newer recycled-uPVC solutions, with better acoustic insulation and smart ventilation integration, are getting traction inside publicly funded retrofit schemes. Firms that invest in automated fabrication and closed-loop recycling processes seem more ready to win long-term supply deals. That’s largely because sustainability compliance is becoming a procurement must, not just an optional selling point.
What Has the Impact of Artificial Intelligence Been on the United Kingdom uPVC Windows and Doors Market?
Artificial intelligence and advanced digital manufacturing systems are kind of reshaping how operations run across the United Kingdom uPVC Windows and Doors Market, mostly by boosting fabrication precision, installation planning, and also supply chain efficiency. In practice, manufacturers are using AI enabled production software more often… to optimize profile cutting, cut down material waste, and automate quality checks during fabrication . Instead of only relying on manual routines, computer vision systems now catch frame alignment defects and glazing inconsistencies quicker than typical inspections, which helps trim rework costs and also reduce those production delays.
At the same time, machine learning models are getting better at demand forecasting and inventory planning. Firms look at past order patterns, seasonal construction cycles , plus regional retrofit activity, so they can handle resin procurement and fabrication schedules more smoothly. Some installers even lean on AI assisted design platforms that run accurate thermal performance simulations and generate customized installation recommendations for homeowners and contractors. Because of this, quotations get prepared faster and installation mistakes tend to drop.
Operationally, automated fabrication lines have improved production consistency , while lowering labor dependence during times when skilled workforce shortages show up. Digital scheduling systems too shortened project turnaround times, especially for big retrofit contracts where timelines get tight.
That said, adoption is still uneven. Smaller fabricators can get stuck with high integration costs and fragmented legacy manufacturing systems. And the limited interoperability between older machinery and these AI driven software platforms keeps slowing the wider digital shift across the sector.
Key Market Trends
- Triple-glazed uPVC systems started getting more mainstream traction after the 2022 energy price shocks , and that pushed most homeowners into a deeper focus on long term heating cost reduction.
- Recycled PVC content usage actually grew a lot between 2023 and 2026 , since resin price volatility kept squeezing manufacturer margins across the UK market.
- In England, retrofit programs sped up the replacement demand. Residential renovation projects then became more than 70% of all installations in 2025, kinda obviously the biggest driver.
- Hybrid aluminum-uPVC door systems really gained ground after 2024, especially with premium housing developers. They wanted better durability and a stronger thermal insulation outcome , for the whole envelope.
- Automated fabrication technologies cut production waste by roughly 10%–15% across the bigger UK profile manufacturing facilities after 2023.
- Housing associations increased their buying of energy-efficient window systems , as government supported decarbonization funding expanded social housing renovation work.
- Eurocell also strengthened its premium product catalog through the Alunet acquisition, and expanded hybrid-frame options plus aluminum compatible solutions.
- Flush-fit window profiles got more popular after 2024, because people wanted heritage style visuals without losing the insulation performance.
- Digital quotation tools and AI assisted installation planning platforms reduced surveying errors too, while also making contractor scheduling more efficient.
- Manufacturers began localizing production and recycling operations more often after supply chain disruptions showed, pretty clearly, how dependent they were on imported raw material inputs.
United Kingdom uPVC Windows and Doors Market Segmentation
By Product Type
uPVC Windows still seem to hold the dominant market position, because residential retrofit activity across the United Kingdom keeps putting more emphasis on thermal insulation and low-maintenance frame systems. Also the replacement demand from older housing stock stays strong, which helps drive big installation volumes in both suburban and urban residential projects. Casement Windows end up in the second-largest spot, mainly because many traditional British housing designs still like outward-opening window systems, and they bring better ventilation plus stronger sealing performance. Sliding Doors, and Bi-fold Doors, keep showing quicker growth too, due to people choosing open-plan living more often, along with residential layouts that connect toward gardens. uPVC Doors meanwhile stay fairly steady across residential and light commercial use, since multi-point locking systems and weather resistance lift the long-run operational value.
uPVC Windows are expected to keep leading structurally too, as energy-efficiency regulations and retrofit funding programs continue encouraging replacement. Bi-fold Doors and Sliding Doors are likely to grow the fastest in the premium tier, because higher-income homeowners are increasingly prioritizing aesthetics, daylight optimization, and indoor-outdoor integration. Tilt & Turn Windows are also becoming more noticeable in modern apartment developments, for example because ventilation control improves, and safety functionality is better. Product developers and fabricators are expected to put more money into recycled profile materials smart-lock integration, and higher-performance glazing compatibility, just to keep long-term competitiveness in good shape.
By Application
Residential Buildings keep the dominant market place, mostly because home renovation and insulation improvement programs still churn out strong replacement need all over the country’s older housing stock. The big retrofit work, especially tied to heating-efficiency upgrades , keeps the installation numbers for windows, entrance doors, and patio systems moving along. Renovation Projects stay in the second-largest spot too, since property owners are leaning toward modernizing what already exists rather than jumping into new construction, even when economic uncertainty is kind of hovering around. Commercial Buildings keep showing steady growth, because offices, schools, and healthcare facilities are putting money into energy-efficient façade upgrades, which helps day to day operations and also supports regulatory compliance. Industrial Buildings are a bit more selective, more or less, with adoption centered on durability, security, and environmental resistance.
Residential applications are expected to keep the market lead as long-term decarbonization goals keep pushing insulation-first modernization of existing buildings. Smart Homes are set for the fastest expansion, mainly because automated ventilation solutions , sensor-integrated locking approaches, and connected glazing technologies are getting easier to access commercially. Commercial renovation demand is also likely to strengthen as workplace modernization and sustainability reporting requirements keep rising across institutional infrastructure projects. Investors and manufacturers are expected to focus on premium residential systems and digitally integrated building solutions, the kind that can support smart energy management environments without fuss.
To learn more about this report, Download Free Sample Report
By Glass Type
Double-glazed Windows seem to hold the dominant market position, mainly because cost-effective thermal insulation and that pretty universal compatibility with residential replacement projects keeps showing up in a lot of bids. In other words , higher installation volumes across mid-range housing developments plus retrofit work are still nudging demand toward something stable. Triple-glazed Windows keep the second-largest position largely on the strength of better insulation, and also because acoustic performance is improved, especially in colder regions and in high-noise urban areas. Laminated Glass keeps gaining traction too, mostly for premium residential and commercial setups where safety, reduced sound transmission and security performance are ongoing procurement priorities that matter. Tempered Glass is more selective, like it shows up most within sliding systems, commercial entrance openings , and bigger glazed structures where stronger impact resistance is required.
Double-glazed systems are expected to stay in volume leadership , because affordability and regulatory compliance are continuing to help mass-market adoption. Triple-glazed Windows are likely to pick up the fastest growth in the premium segment, since heating-efficiency rules keep getting tighter and long-term energy savings become more financially compelling. Laminated Glass should also keep expanding at a steady pace within urban housing developments and institutional infrastructure projects, particularly where occupant safety and acoustic insulation are emphasized. Glass manufacturers and fabricators are expected to put more effort into lightweight thermal coatings, solar-control technologies, and added durability solutions— all of that to lift overall energy performance and lifecycle efficiency.
By Distribution Channel
Dealers & Distributors hold the dominant market position , mostly because regional installation networks and contractor relationships stay right in the middle of procurement choices, across residential projects and renovations. The established distributor routes also help with faster product availability, solid technical consultation, and localized after-sales service , which is kind of a big deal. Direct Sales keep a second-largest position though, since bigger developers, housing associations, and commercial contractors increasingly talk straight with manufacturers when they need large volume procurement contracts.Specialty Stores still carry steady demand by giving premium product consultation, plus customized design offerings, so customers feel more “guided”. Online Retail looks smaller by comparison, but it keeps growing gradually , especially as digital quotation platforms and remote product comparison tools make it easier for customers to reach information, even from a distance.
Dealers & Distributors are also expected to keep that structural importance because localized installer ecosystems continue influencing buying habits across residential markets , in a pretty direct way. Online Retail should see the fastest expansion, as homeowners more often research specifications, compare thermal-performance ratings, and ask for virtual consultations via digital platforms. Direct manufacturer engagement is likely to grow too, particularly in commercial and public-sector retrofit work where customized specification handling matters , along with long-term supply agreements that need to stay stable.Over the forecast period, distribution strategies will increasingly reward firms that can blend digital sales infrastructure, technical advisory services, and quick fulfillment capability across regional markets , not just one or two of those things.
What are the Key Use Cases Driving the United Kingdom uPVC Windows and Doors Market?
The biggest use case within the United Kingdom uPVC Windows and Doors market is still basically residential retrofit and replacement work. A lot of older UK homes need better insulation performance so they can line up with newer energy-efficiency requirements, so uPVC windows and doors end up being the go to choice for cutting down heat loss while also keeping maintenance costs lower than before, kind of straightforward.
On top of that, commercial renovation projects keep pushing forward, especially across schools, healthcare facilities and office buildings. In these cases property owners are swapping worn out frames for higher performance glazing systems, mainly to boost overall building efficiency scores, and also to make sure they are compliant with refreshed environmental expectations. Social housing providers matter too, since public retrofit funding more and more often focuses on thermal-efficiency upgrades, even when budgets get tight.
Looking ahead, some emerging applications are showing up like smart ventilation integrated window systems, plus acoustic insulation installations near busy urban transportation routes. There is also a growing pull for recycled-content uPVC products in public-sector procurement, where sustainability metrics are becoming required in construction tender rules, and everyone seems to be checking them.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 1124.3 Million |
|
Market size value in 2026 |
USD 1178.3 Million |
|
Revenue forecast in 2033 |
USD 1647.4 Million |
|
Growth rate |
CAGR of 4.90% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United Kingdom |
|
Key company profiled |
VEKA, Rehau, Eurocell, Deceuninck, Aluplast, Kommerling, Fenesta, Andersen, Pella, Internorm, Epwin, Safestyle UK, Anglian, Everest, Duroplast |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (uPVC Windows, uPVC Doors, Sliding Doors, Casement Windows, French Doors, Tilt & Turn Windows, Bi-fold Doors, Others); By Application (Residential Buildings, Commercial Buildings, Industrial Buildings, Renovation Projects, Smart Homes, Others); By Glass Type (Double-glazed Windows, Triple-glazed Windows, Laminated Glass, Tempered Glass, Others); By Distribution Channel (Direct Sales, Dealers & Distributors, Online Retail, Specialty Stores, Others) |
Which Regions are Driving the United Kingdom uPVC Windows and Doors Market Growth?
England still feels like the strongest region in the United Kingdom uPVC Windows and Doors Market, not only because it’s the dominant bit, but mainly because it has the country’s largest clump of aging homes plus a steady retrofit rhythm. When building efficiency rules are pushed hard, replacement demand kind of speeds up, especially across town and out-of-town housing sites. London, the Midlands, and the Southeast keep churning out big installation numbers from renovation-led construction spend. There’s also this advantage of a mature fabrication and distribution setup, so delivery and on-site installation capacity stays quick, and pretty workable.
Scotland comes in next as the second-largest contributor, yet the way it moves is a bit different from England. Growth there seems more tethered to public-sector energy-efficiency programs than to private renovation spending. Housing decarbonization efforts plus tougher insulation compliance standards have formed pretty steady purchasing pipelines for contractors and suppliers. Demand is comparatively steady too, partly because local authorities keep putting money into social housing modernization work. That level of consistency gives manufacturers order flows they can plan around, even when the overall construction market gets wobbly.
Wales is turning out to be the fastest growing regional market, largely driven by stronger housing retrofit programs and local sustainability investments that kicked in after 2024. Extra funding for residential energy upgrades, and the push to modernize older housing, has opened fresh doorways for regional installers and profile suppliers. Smaller local fabricators are also leaning into partnerships with bigger national brands, so product availability improves and technical certification coverage becomes broader.
Who are the Key Players in the United Kingdom uPVC Windows and Doors Market and How Do They Compete?
Competition in the United Kingdom’s uPVC Windows and Doors market is still fairly fragmented in practice, with big profile makers rubbing shoulders with regional fabricators and installation specialists. Most firms don’t just undercut on price, more they separate on thermal efficiency performance, fabrication quality, recycling capability, and how far their installer network really reaches. The more established manufacturers keep trying to defend market share via vertically integrated distribution, plus ongoing development of premium product lines, while the smaller outfits tend to lean into customization, and a quicker, more local type of responsiveness.
VEKA stays competitive using high-performance profile systems and very solid ties with independent fabricators all across the UK. They also lean hard into recycled-material integration, together with stronger insulation performance, to match up with the tightening building standards people keep talking about. Rehau sets itself apart with engineered profile technology, flush-fit style aesthetics, and premium glazing compatibility, mostly aimed at higher-end residential renovation projects. Eurocell, on the other hand, leans on its vertically integrated manufacturing and distribution model, which helps keep pricing flexibility intact and preserves nationwide installer access, and it also pushes further into hybrid systems through acquisitions.
Deceuninck is more sustainability-led in its positioning , boosting the use of recycled PVC and supporting lower-carbon manufacturing approaches. Epwin Group, meanwhile, improves competitiveness through a wide-ranging product portfolio, plus partnerships with regional installers, and that helps it move faster into localized retrofit opportunities.
Company List
- VEKA
- Rehau
- Eurocell
- Deceuninck
- Aluplast
- Kommerling
- Fenesta
- Andersen
- Pella
- Internorm
- Epwin
- Safestyle UK
- Anglian
- Everest
- Duroplast
Recent Development News
In March 2026, Eurocell announced continued integration and expansion of its Alunet acquisition. The move strengthened its hybrid aluminum and uPVC product capabilities while supporting premium residential renovation growth in the UK market.https://www.marketscreener.com
In May 2026, Eurocell reported operational investments and strategic improvements despite subdued UK housing activity. The company expanded cost-control initiatives and fabrication optimization to offset weak renovation demand and supply-chain volatility.https://www.ajbell.co.uk/news/articles/eurocell-warns-subdued-trading-alunet-acquisition-boosts-
What Strategic Insights Define the Future of the United Kingdom uPVC Windows and Doors Market?
The United Kingdom uPVC windows and doors market seems to be slowly, kind of, moving toward a retrofit led sustainability driven growth approach, sort of centered on thermal performance, recycled materials, and those premium performance glazing systems. The main push behind this is the UK’s long term housing decarbonization agenda, which keeps tying building compliance rules with real energy efficiency spending. Still, there’s a not so obvious danger in it too, like the sector is getting more exposed to limits in recycled PVC supply, plus the ever wobbly polymer prices, and that combo could squeeze manufacturer margins even if installation volumes keep climbing.
At the same time, a new opening is quietly forming around smart ventilation integrated window systems, aimed at airtight retrofit housing projects, where indoor air quality is getting more attention. This segment is not really fully tapped yet, but it could start catching on as building regulations keep changing. Businesses should really put money into local recycling infrastructure and automated fabrication technologies too, because day to day operational efficiency and sustainably sourced materials will end up deciding procurement wins across both public and private retrofit contracts.
United Kingdom uPVC Windows and Doors Market Report Segmentation
By Product Type
- uPVC Windows
- uPVC Doors
- Sliding Doors
- Casement Windows
- French Doors
- Tilt & Turn Windows
- Bi-fold Doors
- Others
By Application
- Residential Buildings
- Commercial Buildings
- Industrial Buildings
- Renovation Projects
- Smart Homes
- Others
By Glass Type
- Double-glazed Windows
- Triple-glazed Windows
- Laminated Glass
- Tempered Glass
- Others
By Distribution Channel
- Direct Sales
- Dealers & Distributors
- Online Retail
- Specialty Stores
- Others
Frequently Asked Questions
Find quick answers to common questions.
The expected United Kingdom uPVC Windows and Doors Market size for the market will be USD 1647.4 Million in 2033.
Key segments for the United Kingdom uPVC Windows and Doors Market are By Product Type (uPVC Windows, uPVC Doors, Sliding Doors, Casement Windows, French Doors, Tilt & Turn Windows, Bi-fold Doors, Others); By Application (Residential Buildings, Commercial Buildings, Industrial Buildings, Renovation Projects, Smart Homes, Others); By Glass Type (Double-glazed Windows, Triple-glazed Windows, Laminated Glass, Tempered Glass, Others); By Distribution Channel (Direct Sales, Dealers & Distributors, Online Retail, Specialty Stores, Others).
Major United Kingdom uPVC Windows and Doors Market players are VEKA, Rehau, Eurocell, Deceuninck, Aluplast, Kommerling, Fenesta, Andersen, Pella, Internorm, Epwin, Safestyle UK, Anglian, Everest, Duroplast.
The United Kingdom uPVC Windows and Doors Market size is USD 1124.3 Million in 2025.
The United Kingdom uPVC Windows and Doors Market CAGR is 4.90% from 2026 to 2033.
- VEKA
- Rehau
- Eurocell
- Deceuninck
- Aluplast
- Kommerling
- Fenesta
- Andersen
- Pella
- Internorm
- Epwin
- Safestyle UK
- Anglian
- Everest
- Duroplast
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
May 2026
Healthcare Polymer Packaging Market
Healthcare Polymer Packaging Market Size, Share & Analysis Report By Packaging Type (Syringes, IV Bottles and Pouches, Clamshells, Blisters, Bottles & Jars, Containers, Tubes, IV Parental Packaging, Others), By Type (Regulated, Non-regulated), By Polymer Type (LDPE (Low-Density Polyethylene), HDPE (High-Density Polyethylene), Homo-polymer (Homo), Random Copolymer (Random), Block Copolymer (Block), PET, Polystyrene, Polyvinyl Chloride, Polyamide/EVOH, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Hydrophilic Tape (Waterstop) Market
Hydrophilic Tape (Waterstop) Market Size, Share & Analysis Report By Type (Bentonite-Based Hydrophilic Tape, Rubber-Based Hydrophilic Tape), By Application (Residential Buildings, Commercial Buildings, Infrastructure Projects), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Metalens Market
Metalens Market Size, Share & Analysis Report By Type (Visible Light Metalens, and Infrared Metalens), By Application (Consumer Electronics, Automotive Electronics, Industrial, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
PBT Resin Market
PBT Resin Market Size, Share & Analysis Report By Type (Reinforced PBT Resin, Unreinforced PBT Resin), By Processing Method (Injection Molding, Extrusion, Blow Molding, Others), By End-User (Automotive, Electrical & Electronics, Consumer Appliances, Industrial Machinery, Medical Devices, Packaging, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031